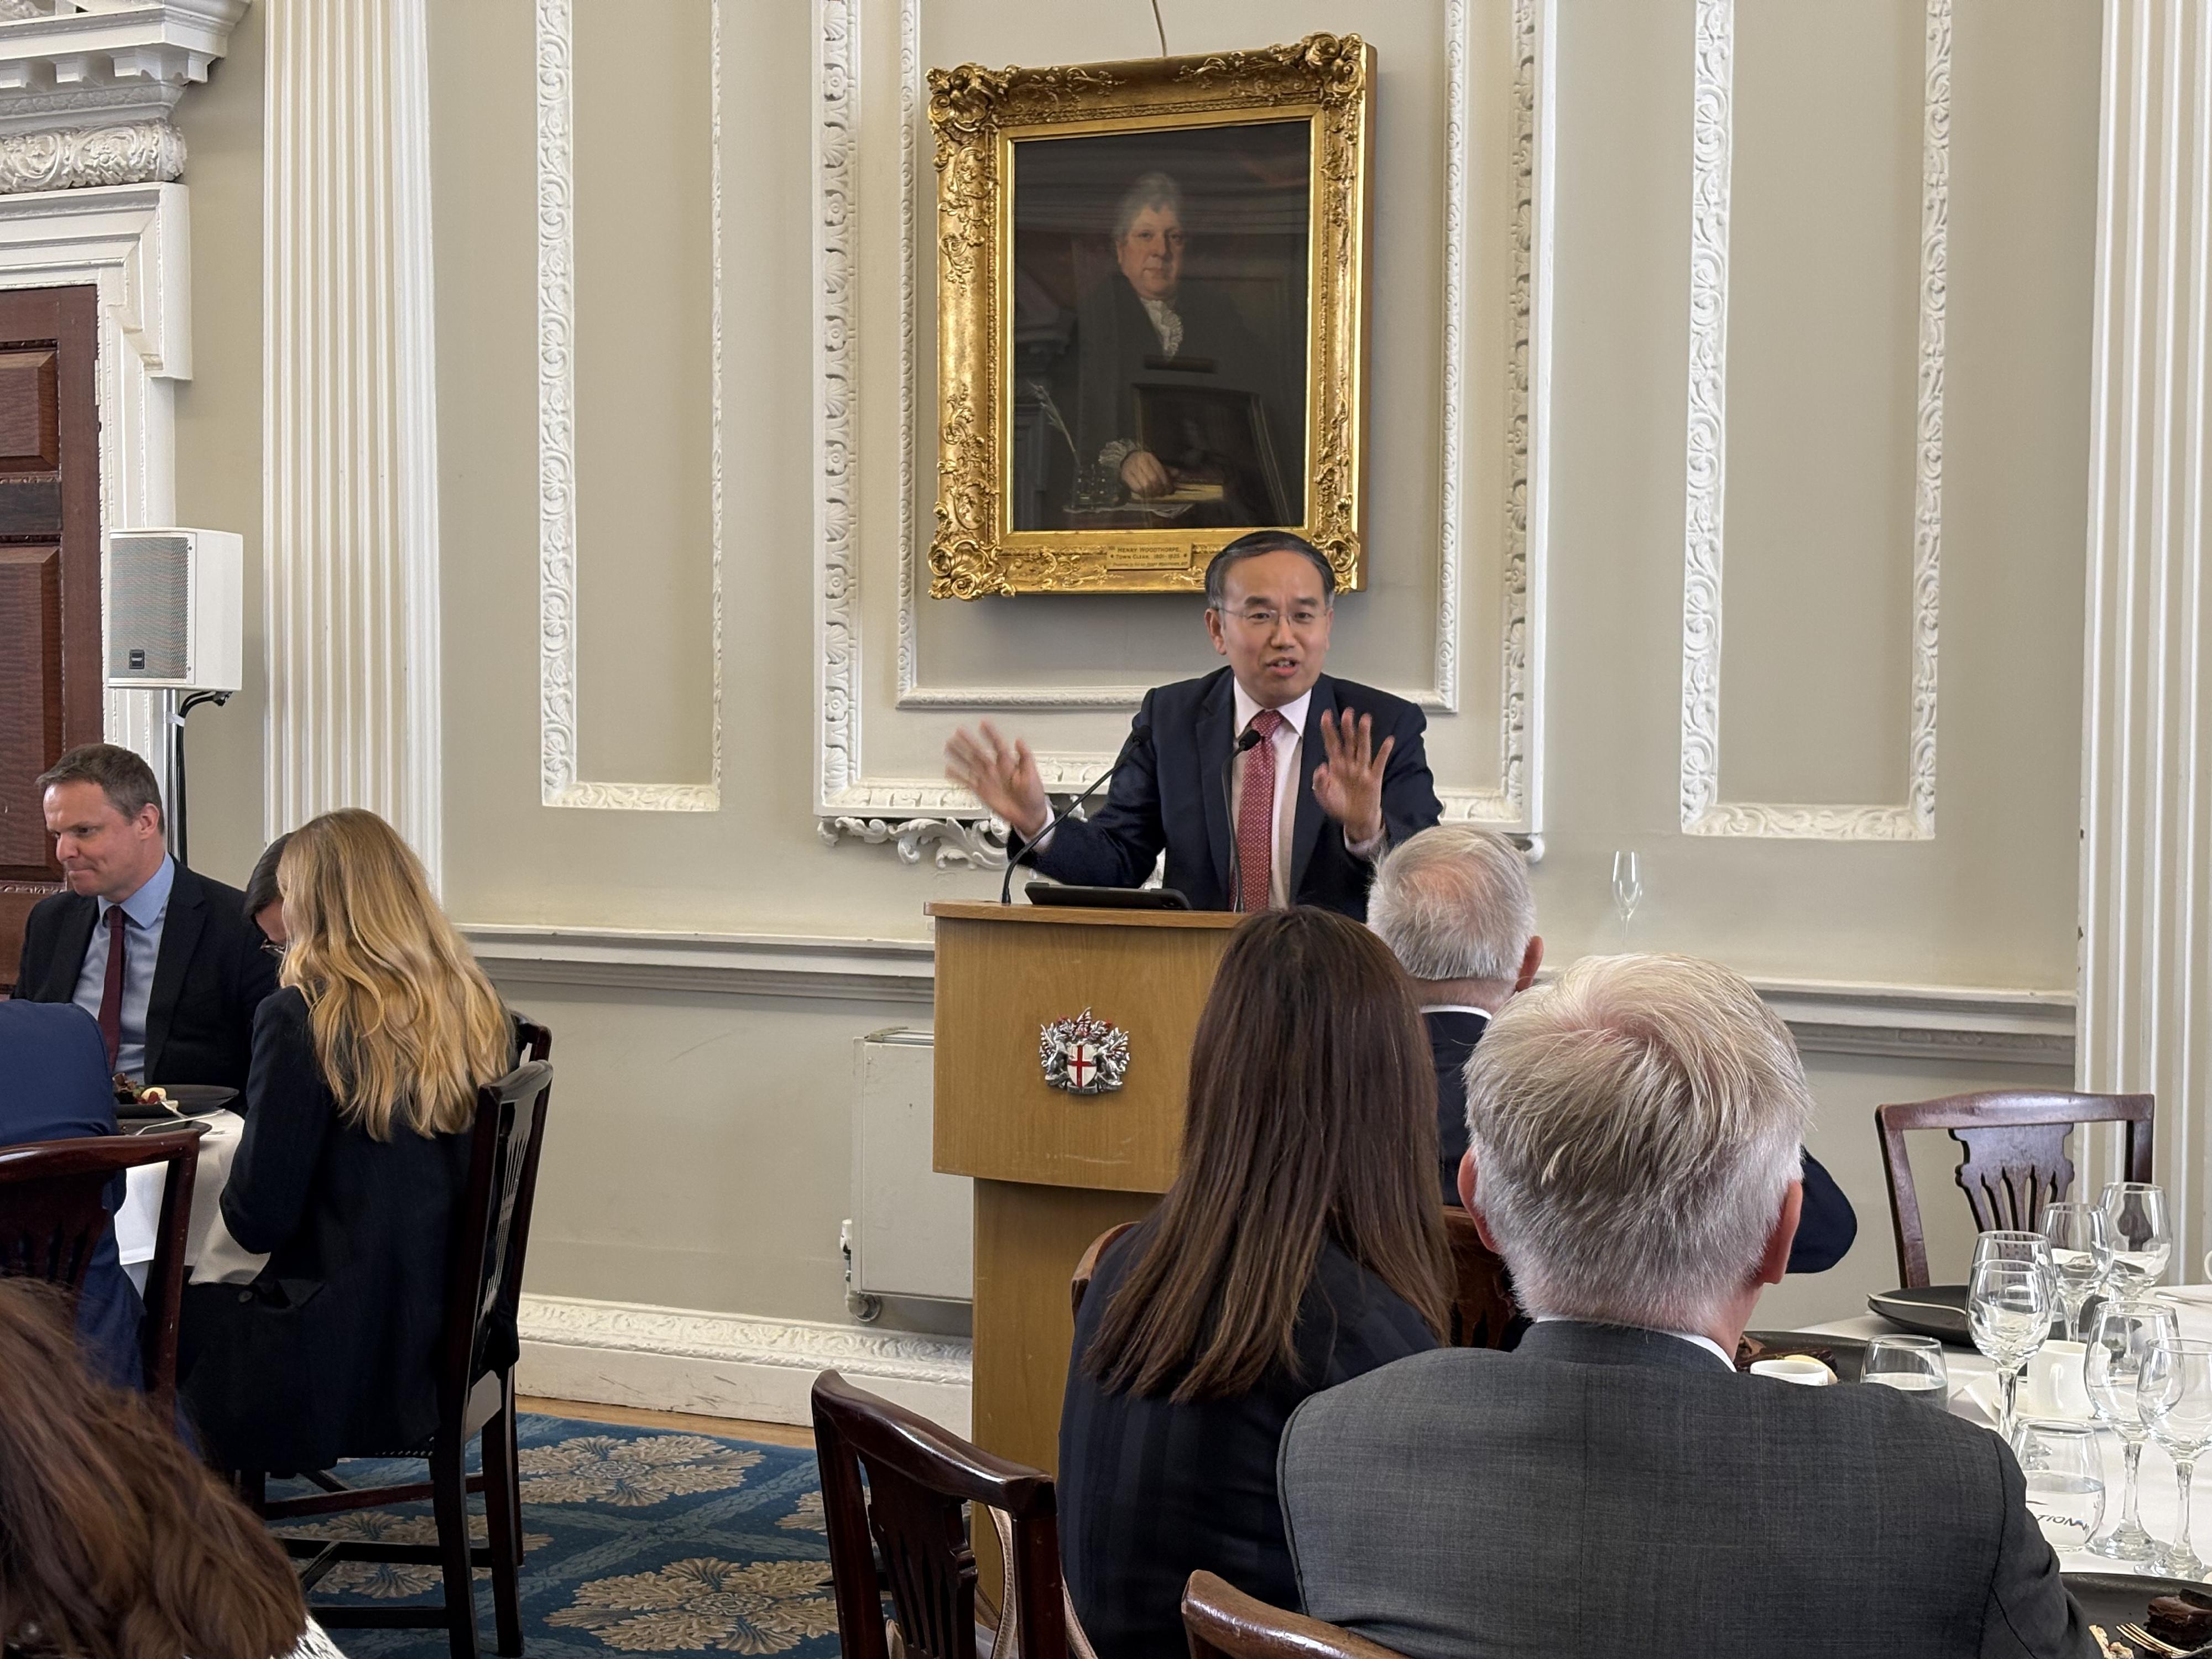Author Archives: hksar gov

SFST’s speech at Hong Kong Association Membership Luncheon in London, United Kingdom (English only) (with photos)

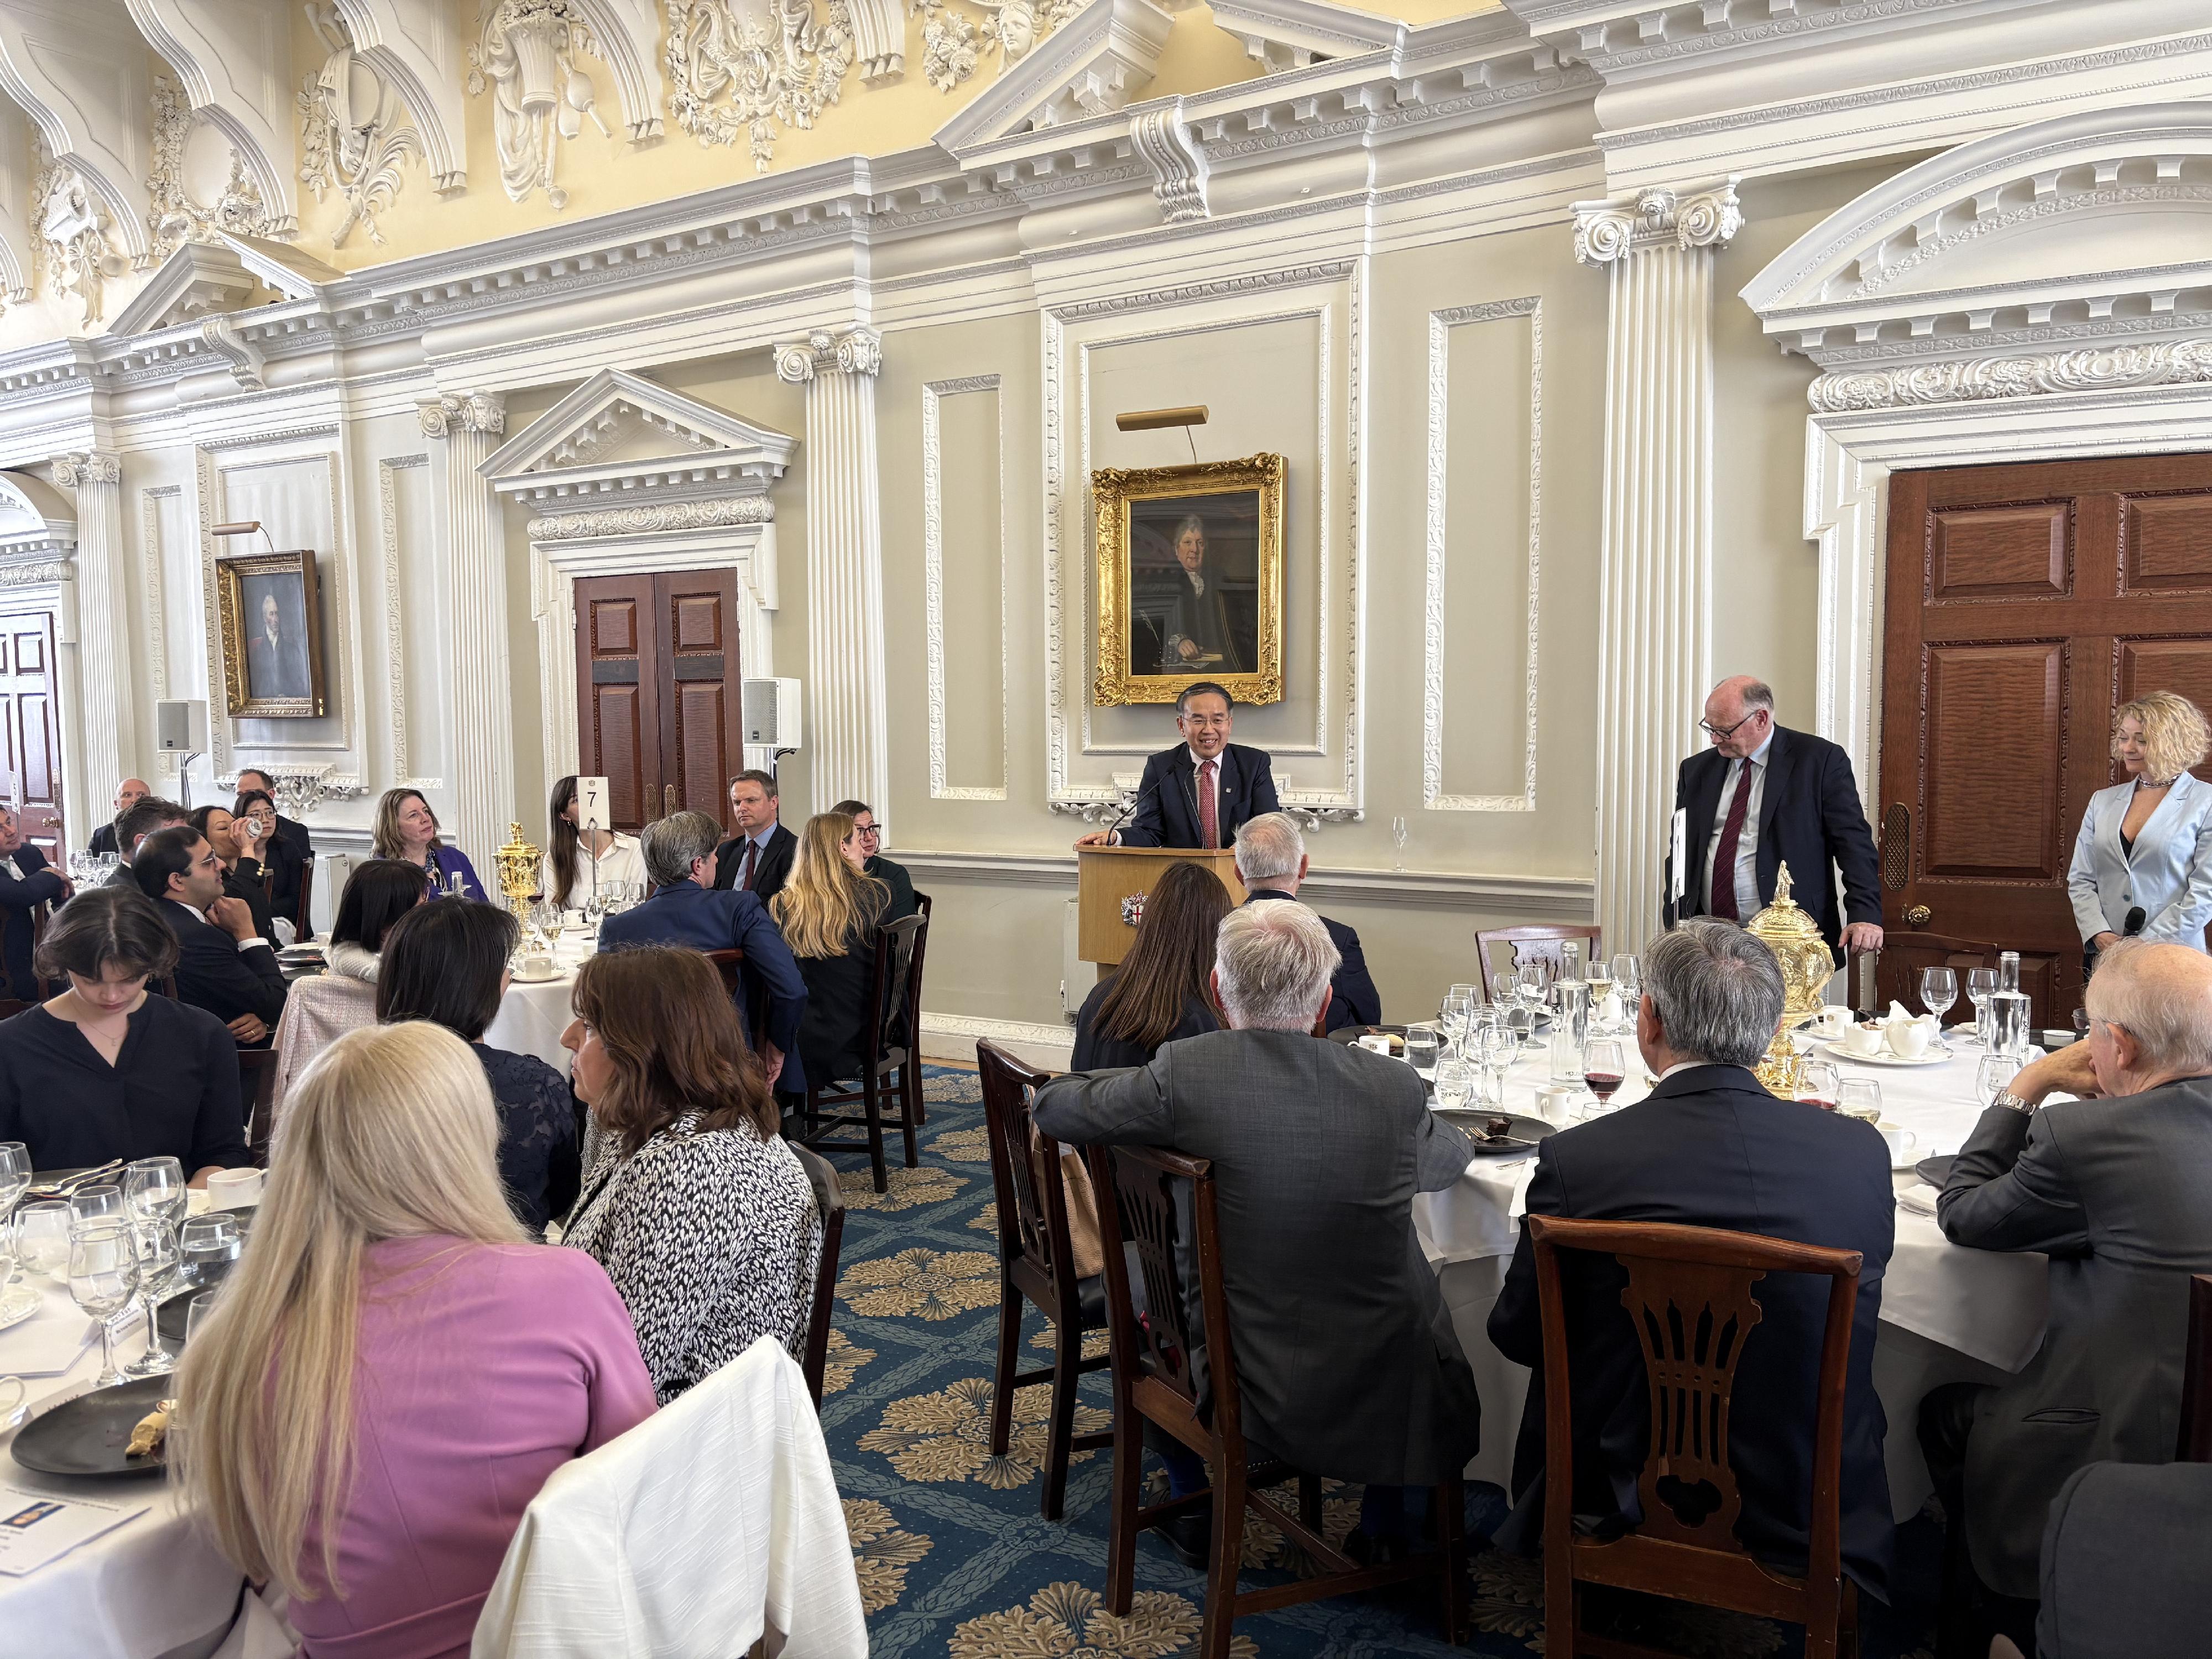
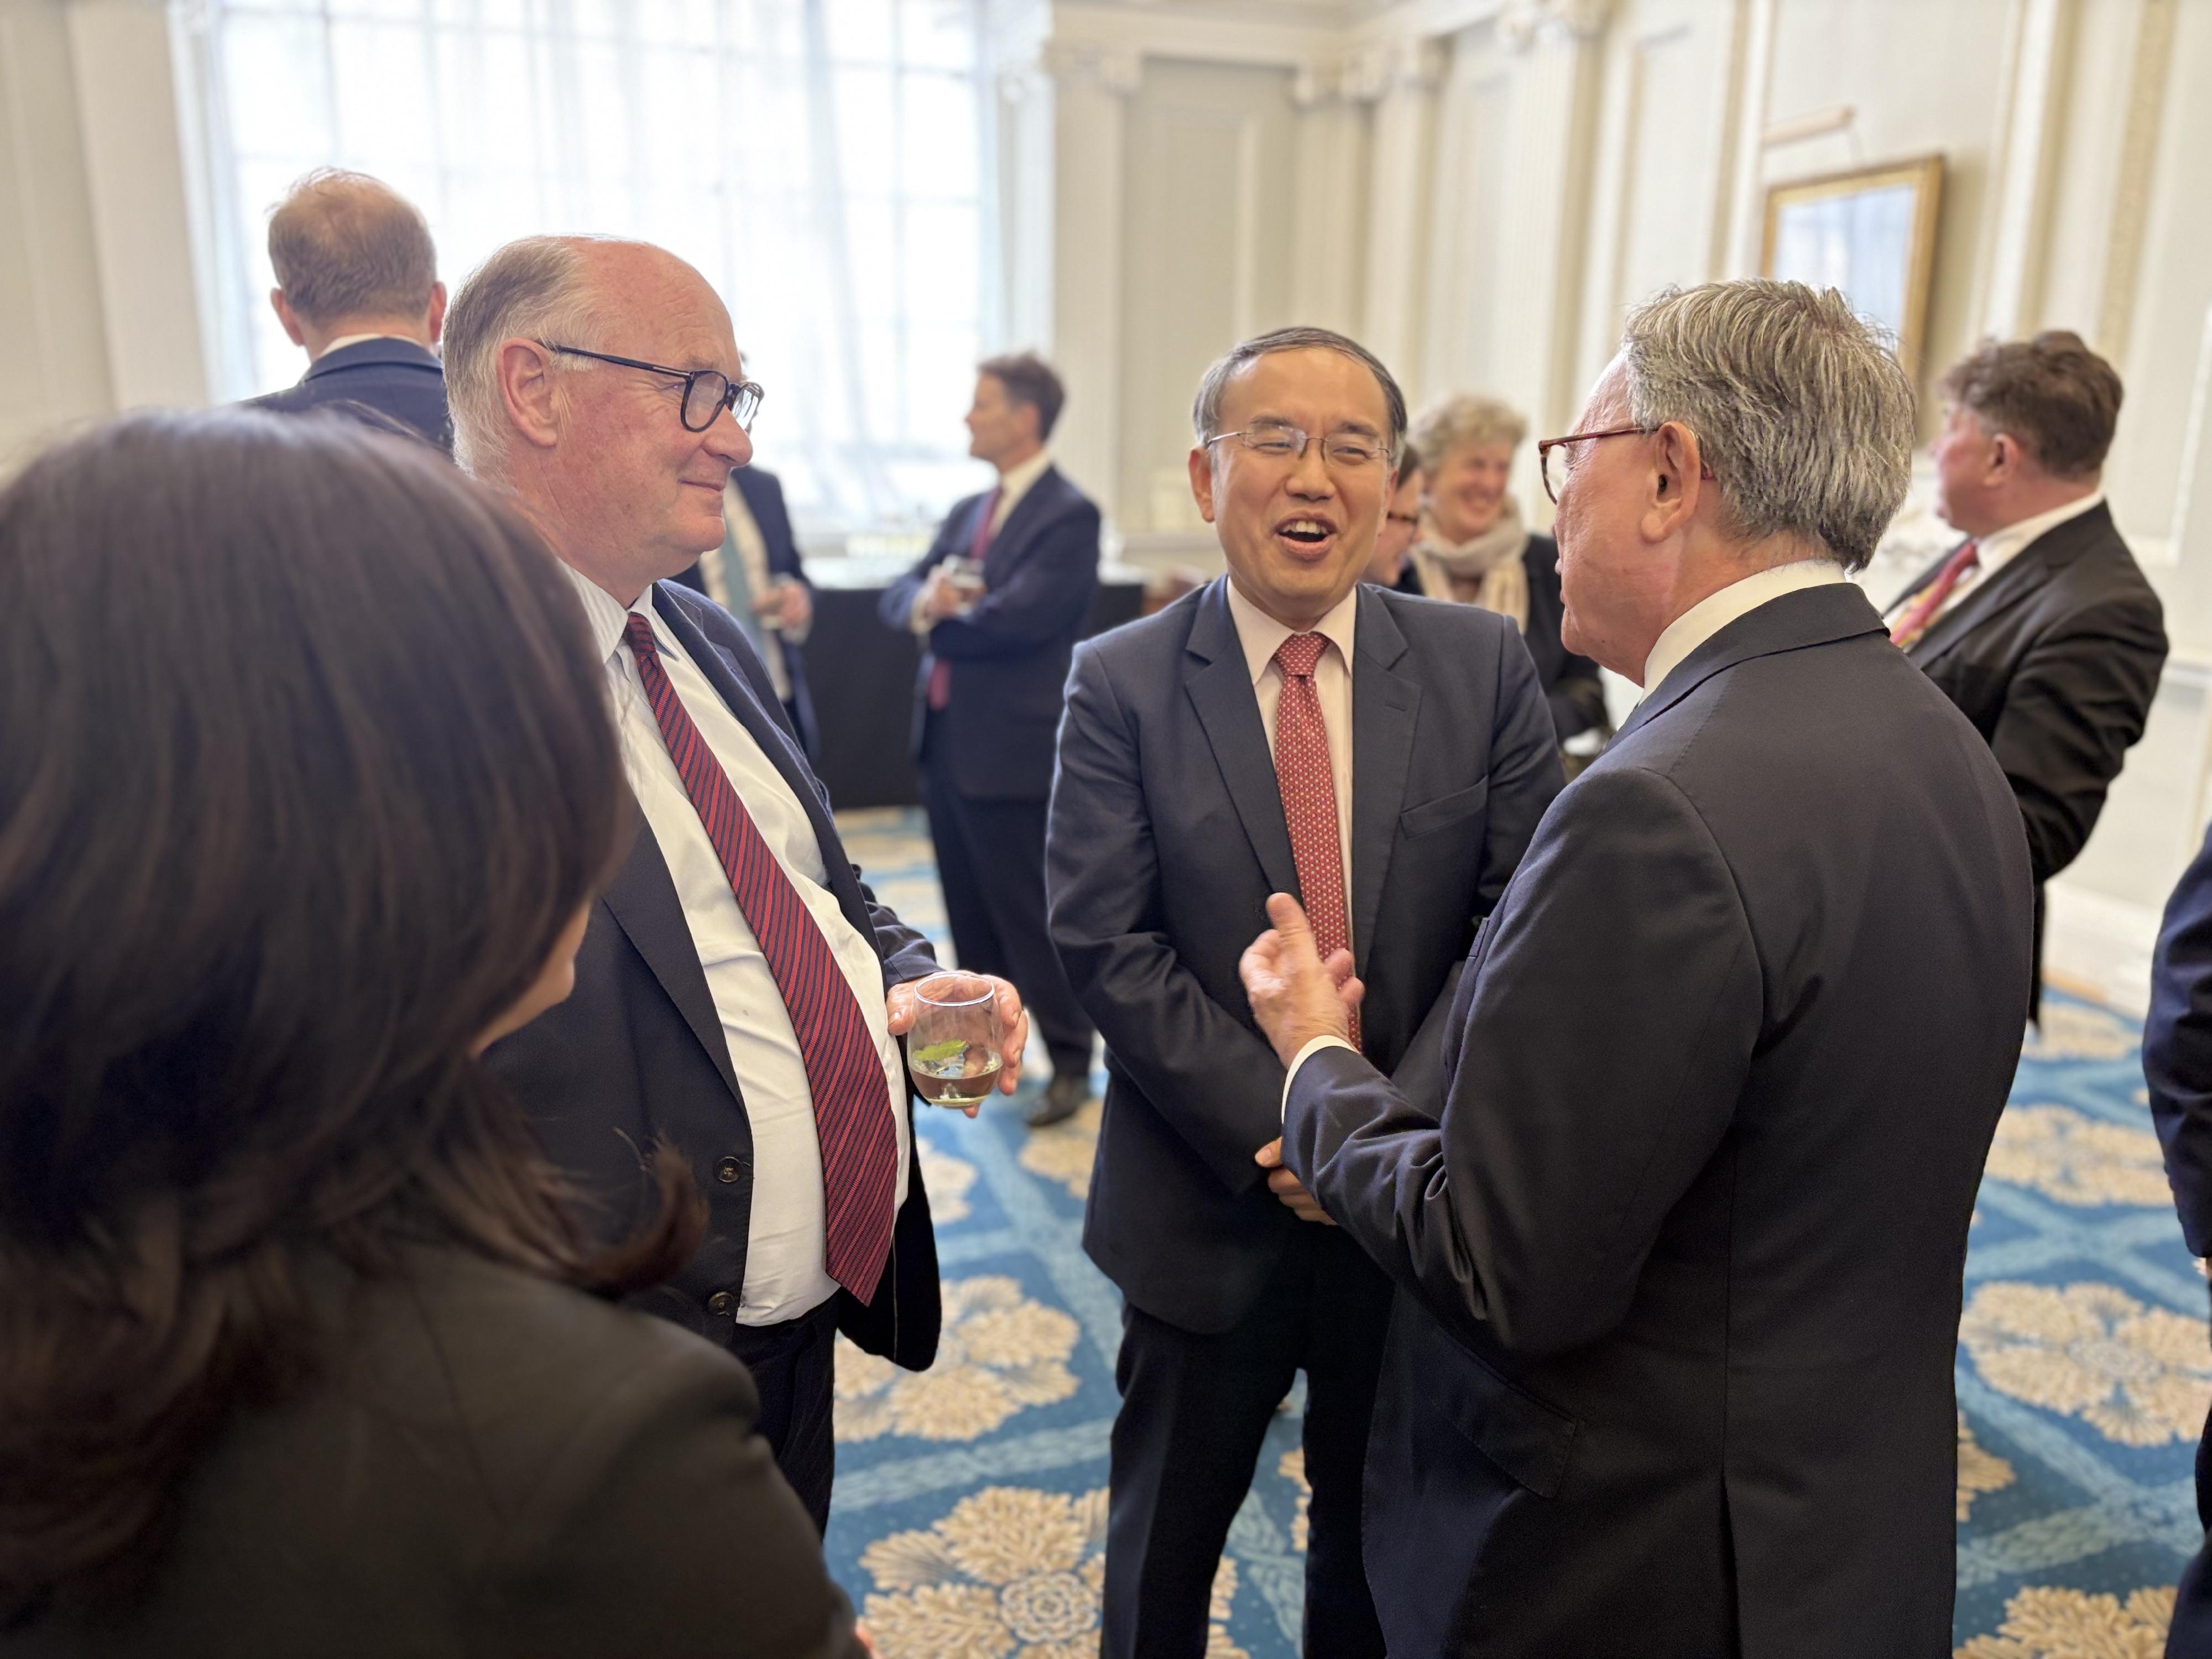
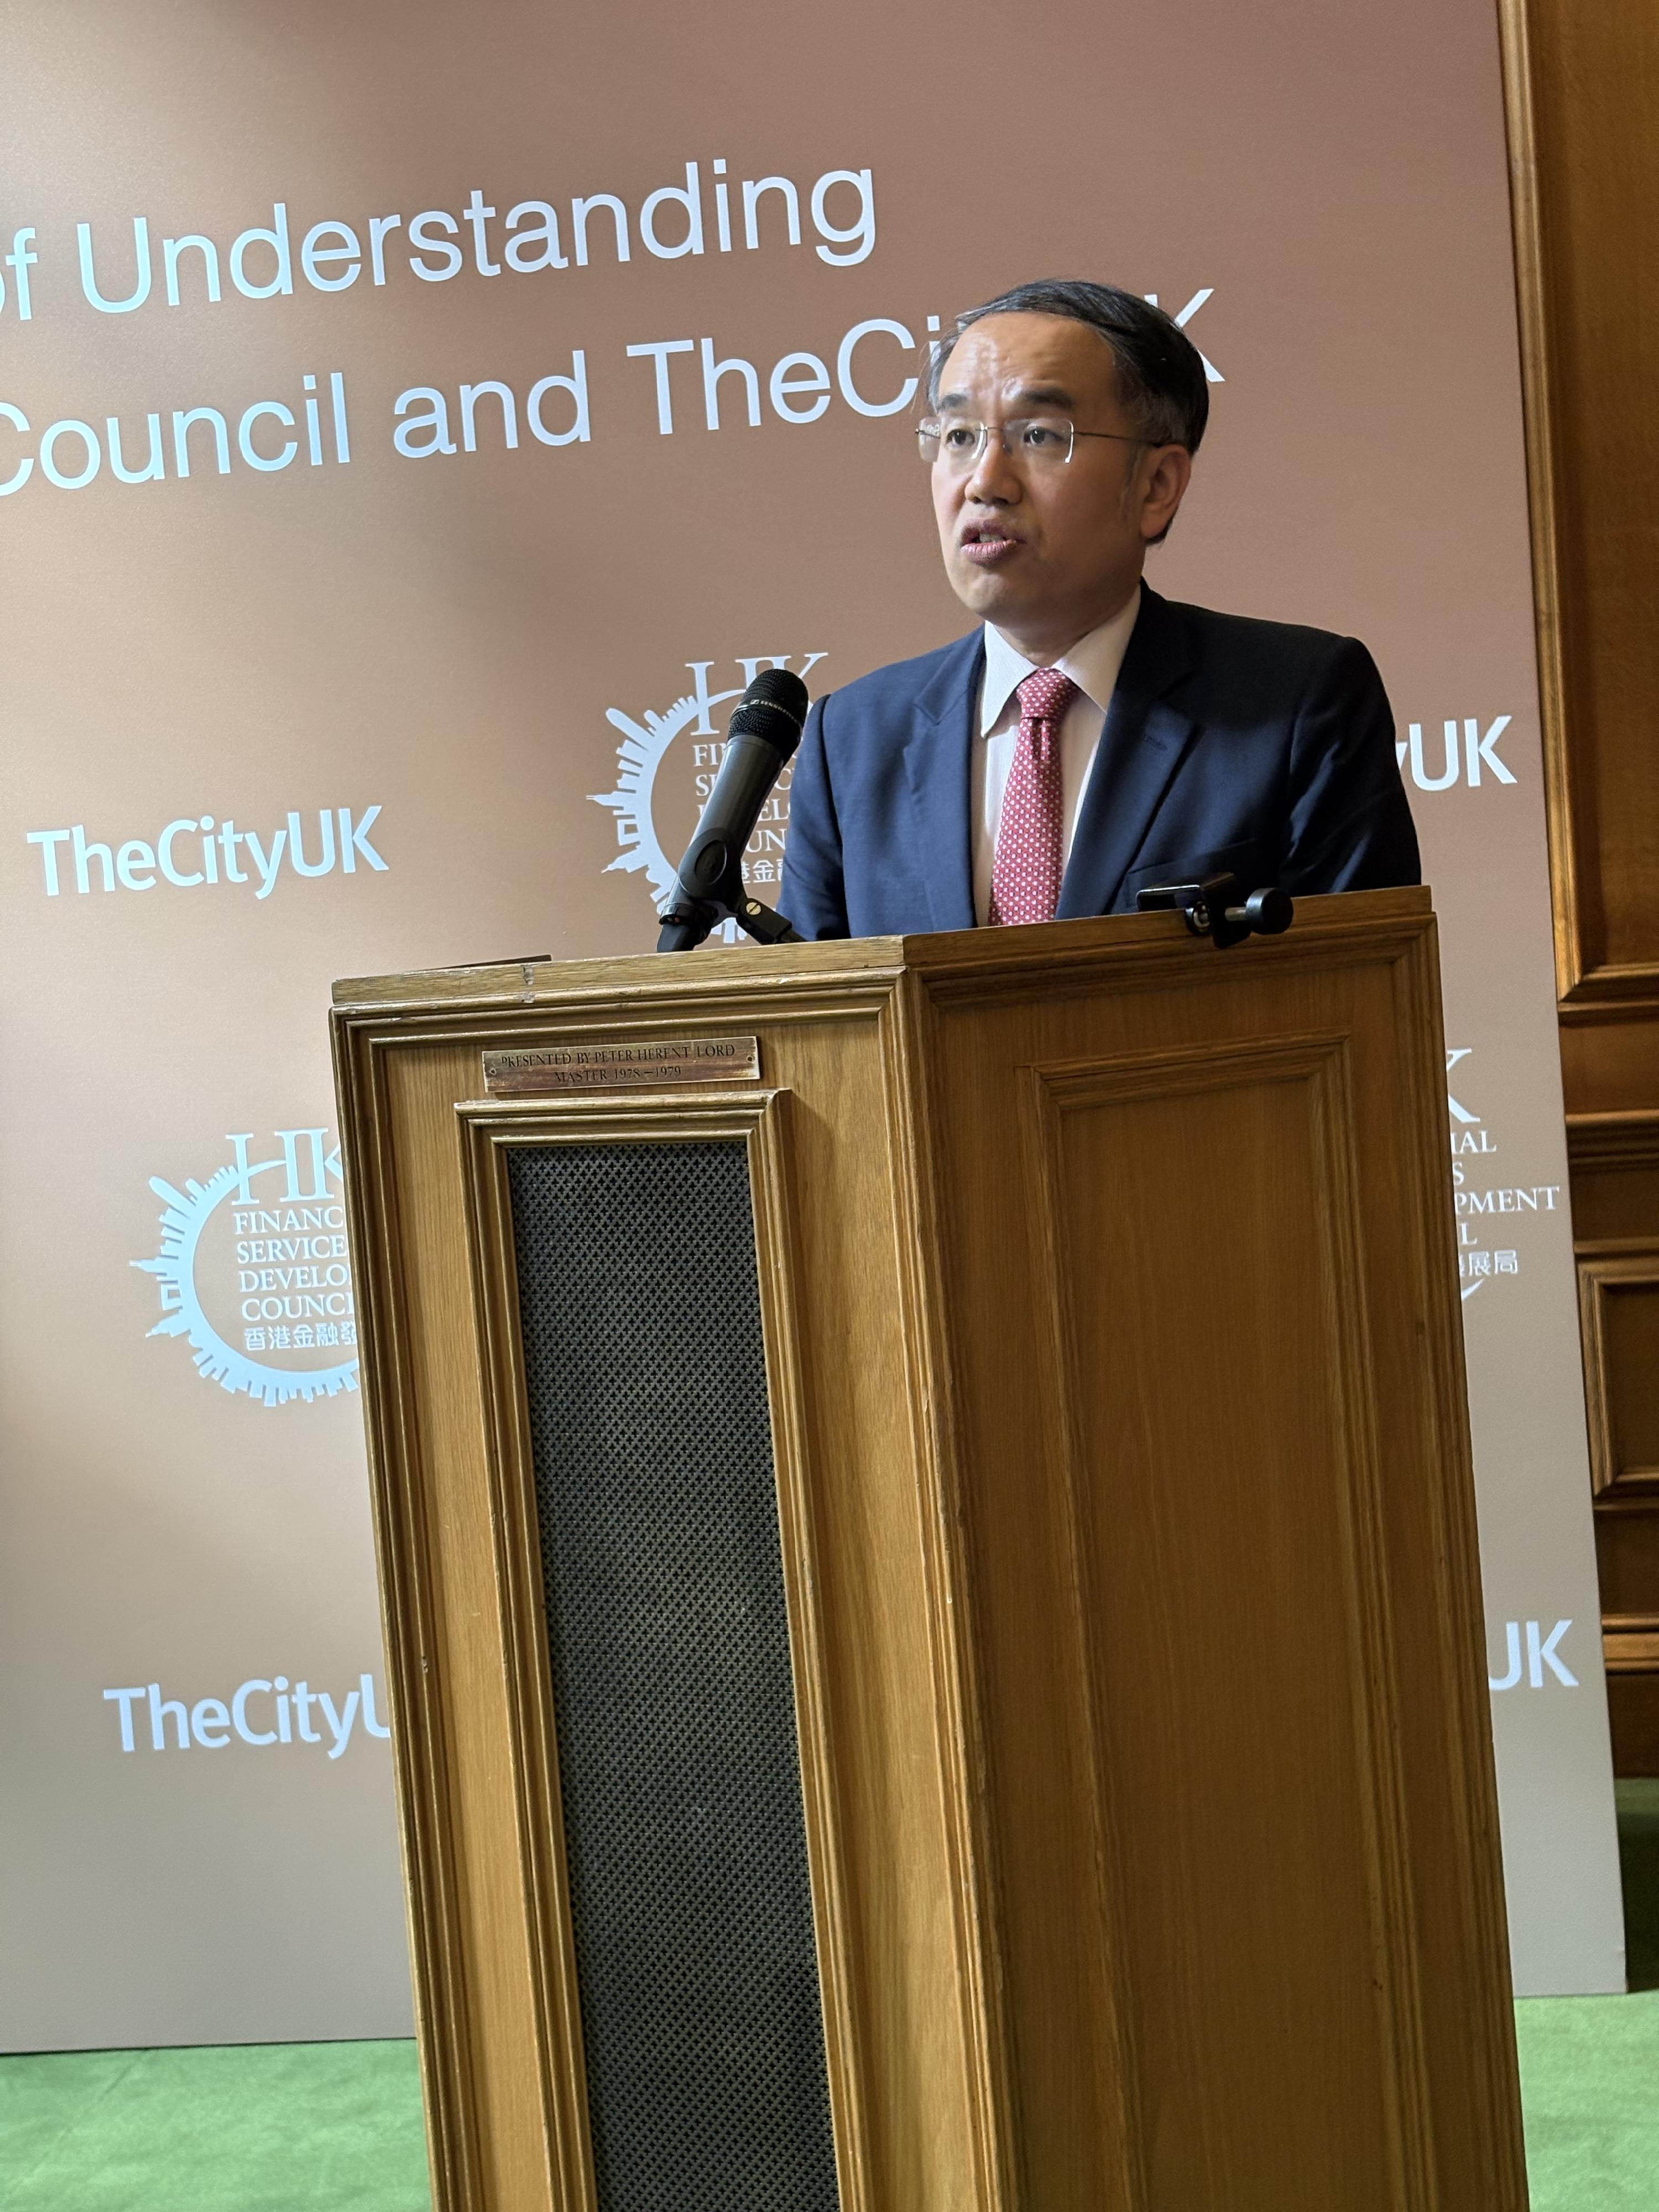
     Following is the speech by the Secretary for Financial Services and the Treasury, Mr Christopher Hui, at the Hong Kong Association Membership Luncheon on “Extending, Embracing, Enhancing – Hong Kong’s Role as a Premier International Financial Centre” in London, the United Kingdom (UK), on June 10 (London time):
 
Lord Mayor (696th Lord Mayor of the City of London, Mr Alderman Alastair King), Sir Douglas (Committee Member of the Hong Kong Association, Chairman of Aberdeen Group, Sir Douglas Flint), distinguished guests, esteemed members of the Hong Kong Association, ladies and gentlemen,
 
     Good afternoon. It is a profound privilege to address you today at this distinguished luncheon hosted by the Hong Kong Association in London. I must say, you are a crowd too difficult to please because you know Hong Kong too well. This organisation’s mission is to champion the enduring business and trading relationship between Hong Kong and the UK which resonates deeply with the Government’s goal of fostering economic collaboration, innovation, and mutual prosperity. To further the efforts, I am here to showcase our city’s unparalleled strengths as a global financial hub and to explore the vast potential for deepening financial co-operation between Hong Kong and the UK. Our shared visions and complementary expertise position us well to forge a partnership that drives transformative growth in an increasingly challenging and also uncertain global economy.
 
     If you may recall, for those people who came two years ago for a similar occasion where I spoke, I tried to group my speech in five alphabet letters, ABCDE. A is about Asia, B is about business as usual, C is about connectivity, D is about digitalisation whereas E is about ESG (environmental, social and governance). These are the five elements at the time I drafted the speech that something Hong Kong could offer to this part of the world. So I am thinking, to this group which is very knowledgeable about Hong Kong, what should I say and how I should structure this speech? Of course I don’t want to get to the next alphabet letter after E, that is why I would stay at E and come with 3Es which are actually the pillars that define Hong Kong’s strategic vision as a premier international financial centre: 1) Extending our financial value chain across equities, fixed income, currencies, and commodities. For those in the banking or financial world, you know what I mean. It’s about EFICC; 2) Embracing new finance through fintech and green finance; and 3) Enhancing offerings for Chinese companies going global through Hong Kong and international firms accessing the Mainland market. These pillars reflect our dynamic approach to navigating global economic and geopolitical challenges, seizing emerging opportunities, and fostering collaboration with partners like the UK. Let me elaborate on each pillar, highlighting our recent achievements and the opportunities they present for strengthening Hong Kong-UK ties.
 
Extending our financial value chain
 
     Hong Kong’s position as a global financial hub is built on its ability to offer a diversified, resilient, and innovative financial ecosystem. By extending our financial value chain across equities, fixed income, currencies, and commodities which can be grouped as EFICC, we are creating a robust platform that serves both regional and international markets, fostering opportunities for collaboration with global partners, including the UK.
 
Equities: a vibrant and forward-looking market
 
     Hong Kong’s equity market has undergone a remarkable transformation over the past decade, driven by bold structural reforms and a commitment to capturing global economic trends. The Hang Seng Index, which is a key barometer of our market’s performance, has demonstrated resilience amid global uncertainties. By May 30, our stock market capitalisation has increased by 24 per cent year on year to over US$5.2 trillion. This growth was propelled, I must say, by a number of key moments this year, including of course the DeepSeek moment when people really recalibrate the value that Chinese investment carry and at the same time also the “victory day” moment when people are seeing the uncertainty in other parts of the world which actually present opportunities to Hong Kong and London. The average daily turnover for the first five months of this year stood at US$31 billion in our market, an increase of 1.2 times over the past year, signaling sustained investor confidence and market liquidity.
 
     Apart from the market performance, we are also trying to reform our capital market to make it more instrumental in positioning Hong Kong as a global hub for new economy and technology companies. Back in 2018, we already introduced the “weighted voting rights” regime, enabling companies with dual-class share structures to list in Hong Kong. As I know, London Stock Exchange is also contemplating something similar to reform your stock market. This reform in Hong Kong attracted technology giants and paved the way for a new era of innovation-driven listings. Simultaneously, we opened our market to pre-revenue biotech firms, transforming Hong Kong into one of the world’s leading fundraising hubs for biotechnology. As a result, the proportion of new economy companies in our stock market has surged from 1.3 per cent in 2018 to approximately 14 per cent by April 2025, with their market capitalisation share rising from 2.8 per cent to about 28 per cent.
 
     Building on this momentum, we introduced the “18C” listing regime in 2023 for specialist technology companies, followed by a dedicated technology enterprises channel launched last month. These initiatives are designed to accelerate the listing of enterprises in the “hard technology” space, enabling them to raise capital in Hong Kong and expand their international presence. These reforms have not only reshaped the structure of our stock market but also aligned it with global economic trends, positioning Hong Kong as a vital partner for UK firms seeking exposure to Asia’s innovation-driven growth.
 
     Moreover, Hong Kong’s capital markets have benefited from the return of Chinese concept stocks, driven by geopolitical developments and Mainland China’s technological advancements. This trend has elevated the weight of technology stocks in our market, further enhancing its attractiveness to global investors. For example, before I came, we welcomed the listing of CATL (Contemporary Amperex Technology Co Limited) which is a major lithium-ion battery manufacturing company serving the world for electric vehicles. For UK financial institutions, Hong Kong offers a gateway to invest in Asia’s burgeoning tech sector, leveraging our deep liquidity and robust regulatory framework.
 
Connectivity and stability
 
     Apart from fundraising, it’s about our strengthened role as a gateway for international investors accessing Mainland China and for Mainland investors diversifying globally. Our “Connect” schemes – Stock Connect, Bond Connect, Wealth Management Connect, and Swap Connect – have facilitated seamless cross-border capital flows. These initiatives have seen significant growth in transaction volumes, product diversity, and risk management capabilities, enhancing both the “quantity” and “quality” of financial connectivity, covering the broad financial value chain across equities, fixed income and currencies.
 
     Stability is also a cornerstone of our financial system, as demonstrated by the performance of the Hong Kong dollar recently. In the first five months of 2025, the Hong Kong dollar largely traded within the strong-side convertibility undertaking range, signifying a robust demand, partly because a lot of money coming to Hong Kong to buy our IPOs (initial public offerings) which are in Hong Kong dollars, and at the same time it is now the season when the listed companies need Hong Kong dollars to give out dividends. So with this background, what we see is operations by our banking regulator where now the banking system aggregate balances rising to US$22 billion by May 30, 2025, a substantial increase from US$5.7 billion at the end of last year. Total bank deposits grew by over 4 per cent in the first four months of 2025, with Hong Kong dollar deposits rising by 4.4 per cent, reflecting strong capital inflows into our banking system. So you have been hearing a lot about capital flight from Hong Kong to others, all these numbers are testaments to how wrong those perceptions are. This stability underscores our role as a trusted financial hub, like that of London, offering a secure environment for UK investors and businesses.
 
     Amid global economic uncertainties, including trade protectionism and unilateral policies, RMB (Renminbi) is gaining prominence as a global transaction and reserve currency. Its share in global payments rose from 2 per cent in 2020 to 4 per cent by the end of 2024, ranking fourth globally, while its share in trade financing increased from 2 per cent to 6 per cent. As the world’s leading offshore RMB hub, Hong Kong is seizing this opportunity by enhancing RMB-denominated investment products and risk management tools. Our plan to integrate RMB-denominated stock trading into Southbound Stock Connect will further support RMB internationalisation in a gradual and prudent manner, creating opportunities for UK financial institutions to engage with RMB-based products and services.
 
Commodities: pioneering a new ecosystem with LME integration
 
     In the commodities sector, Hong Kong is capitalising on the global surge in non-ferrous metals trading, driven by the transition to new energy technologies. In 2024, the London Metal Exchange (LME) recorded trading volumes of 178 million lots, a 20 per cent year-on-year increase, with significant growth in new-energy metals like nickel and cobalt. These metals are critical to industrial transformation and technological advancement, and China remains a pivotal force, with non-ferrous metals trade exceeding US$368 billion in 2024, up 11 per cent from the previous year.
 
     Recognising this potential, our Chief Executive outlined a vision in his Policy Address to create a commodity trading ecosystem in Hong Kong, encompassing warehousing, distribution, trading, testing, certification, insurance, and financial services. A landmark achievement in this regard is our integration into the LME’s global warehouse network in January this year. By bringing storage facilities closer to Mainland China’s industrial heartlands and consumption centres, we are strengthening our role as a central platform for the metals industry. Within months since January this year when we are recognised as a delivery port for the LME contracts, seven warehouses have already been approved, and their operations will commence as early as in July 2025.
 
     This initiative not only enhances Hong Kong’s commodities infrastructure but also creates significant opportunities for UK firms, given the LME’s London-based heritage. The UK’s expertise in commodities trading and Hong Kong’s proximity to Asia’s industrial markets make our partnership a natural fit. By collaborating on warehousing, trading, and related services, we can jointly tap into the growing demand for new-energy metals, supporting global industrial transformation and sustainable development.
 
     By extending our financial value chain across equities, fixed income, currencies, and commodities, Hong Kong is reinforcing its position as a diversified financial hub. We invite UK businesses to leverage our platform to access Asia’s dynamic markets, fostering mutual growth and collaboration in these critical sectors.
 
Embracing new finance: fintech and green finance
 
     The second pillar of our strategy is embracing new finance, particularly in fintech and green finance, to position Hong Kong at the forefront of financial innovation and sustainability. These areas align closely with the UK’s developments in digital finance and sustainable investments, creating fertile ground for partnership.
 
Fintech: pioneering digital assets and stablecoin regulation
 
     Hong Kong’s robust regulatory framework, business-friendly environment, and strategic location make it an ideal hub for fintech innovation. My bureau, FSTB (Financial Services and the Treasury Bureau), in collaboration with financial regulators and industry stakeholders, is pursuing a multipronged strategy to foster a vibrant fintech ecosystem. This includes enhancing financial infrastructures, nurturing talent, strengthening industry connections in Mainland China and overseas, and creating a conducive environment for fintech innovation.
 
     This is my second day here in London and I am hearing a lot about digital assets (DAs). Just days before I embarked on this trip, our Legislative Council has passed the Stablecoins legislation in Hong Kong and it will be enacted on August 1. After that, we will issue a second policy statement about promoting Hong Kong as the digital asset ecosystem.
 
     Looking ahead, we will continue to be a leader in adopting emerging technologies. A 2023 survey revealed that 38 per cent of Hong Kong’s financial institutions adopted generative AI, surpassing the global average of 26 per cent. In October last year, we issued a policy statement on the responsible use of AI in finance, followed by practical guidelines, sandbox schemes, and industry seminars to support institutions in adopting AI responsibly. These initiatives position Hong Kong as a hub for fintech innovation, complementing the UK’s advancements in areas like blockchain and AI-driven financial services.
 
Green finance: driving sustainable development
 
     Moving on to green finance, Hong Kong is committed to mobilising cross-border investments to address climate and sustainability challenges, aligning with global efforts to achieve net zero. Last year, Hong Kong arranged US$43 billion in green and sustainable bonds, capturing 45 per cent of the Asian market and ranking first in the region for seven consecutive years. By March this year, our security regulator authorised around 220 ESG funds, managing US$140 billion in assets, an 80 per cent increase over three years.
 
     Last week we have just issued a new round of Government green bonds and infrastructure bonds, totally around US$3.5 billion, denominated in four currencies, namely HKD (Hong Kong dollars), RMB, USD (US dollars) and EUR (euro). The offering attracted participation from a wide spectrum of investors from more than 30 markets across Asia, Europe, Middle East, and the Americas, with total orders amounting around US$30 billion equivalent, representing an over-subscription of almost nine times. The proceeds from green bond issuance will fund local Government green works projects, and set benchmarks for the market encouraging private-sector participation.
 
     To align with global standards, we launched the Roadmap on Sustainability Disclosure in December last year, providing a clear path for large publicly accountable entities to adopt the International Financial Reporting Standards – Sustainability Disclosure Standards (ISSB Standards) by 2028. This positions Hong Kong among the first jurisdictions to align with global sustainability reporting standards, enhancing transparency and comparability. The roadmap not only reflects our commitment to the global green transition but also offers clarity and guidance to market participants.
 
     On the funding support side, the Green and Sustainable Finance Grant Scheme, which was extended to 2027, subsidises issuance costs for bonds and loans, including transition financing, encouraging industries across the Greater Bay Area and Belt and Road economies to leverage Hong Kong’s platform for low-carbon transitions. So for many of you who are working for business financial institutions or companies, do take this message home that we are subsidising for people who are issuing green bonds and loans in Hong Kong.
 
     These efforts create significant opportunities for UK firms to collaborate with Hong Kong on green finance initiatives, from ESG funds to green technology solutions, leveraging our shared commitment to sustainability and innovation. The UK’s commitment in green finance, combined with Hong Kong’s strategic position in Asia, can drive impactful partnerships in sustainable investment and technology.
 
Enhancing offerings for global and Mainland businesses
 
     The third pillar, enhancing offerings, underscores Hong Kong’s role as a bridge for Chinese companies going global and international firms accessing Mainland China, supported by policies that facilitate cross-border mobility and business expansion.
 
Supporting Chinese companies going global
 
     As Mainland China accelerates its economic opening, Chinese firms are intensifying their global expansion, optimising supply chains and market presence to address geopolitical risks and tap into international markets. Hong Kong is uniquely positioned to support this “going out” strategy, offering financing, supply chain management, and professional services under the “one country, two systems” framework.
 
     Hong Kong’s efforts to strengthen ties with emerging markets further enhance our appeal. In October last year, we facilitated the listing of two Hong Kong-focused exchange-traded funds on the Saudi Exchange, attracting Middle Eastern capital to our markets. The two Saudi-listed ETFs have a combined size of over US$1.9 billion. They are the two largest ETFs listed and are amongst the top traded ETFs on Saudi Stock Exchange. This initiative demonstrates our commitment to connecting traditional and emerging markets, offering UK firms a platform to diversify their investments across Asia and beyond.
 
     Hong Kong’s professional services, for example the Accounting sector, are well-positioned and experienced to meet the needs of Mainland firms going global. The Hong Kong Institute of Certified Public Accountants has earlier compiled a list of firms specialising in supporting global expansion of Chinese companies, and has recently expanded the list from 60 to over 80 firms, connecting Mainland enterprises with international markets for business expansion. Moreover, Hong Kong’s network of 52 Comprehensive Double Taxation Agreements with other tax jurisdictions, with plans for further expansion, provides tax clarity for businesses, enhancing Hong Kong’s appeal as a commercial and investment hub.
 
     UK firms can partner with Hong Kong to support Chinese companies’ international ventures, leveraging our expertise in financing, legal services, and market access. For example, UK financial institutions can collaborate with Hong Kong-based firms to provide advisory services, underwriting, and risk management solutions for Chinese enterprises expanding into Europe and beyond.
 
Facilitating international access to the Mainland
 
     Hong Kong is equally committed to helping international talents, including those from the UK, access Mainland China’s vast market. A facilitating policy introduced in July last year allows non-Chinese Hong Kong permanent residents to obtain a card‑type document with five-year validity. This card enables self-service clearance at Mainland control points without going through manual channels, eliminating the need for arrival cards and significantly enhancing clearance efficiency. This measure, implemented under the “one country, two systems” framework, facilitates business, travel, and family visits, reinforcing Hong Kong’s role as a gateway to the Mainland.
 
     Hong Kong’s professional services, with deep knowledge of Mainland business culture and international expertise, provide comprehensive support for UK firms navigating China’s market. From legal and accounting services to supply chain management, Hong Kong offers a trusted platform for UK companies to establish and grow their presence in Asia.
 
Hong Kong-UK financial co-operation
 
     The complementary strengths between the two markets of Hong Kong and UK create a strong foundation for collaboration. The integration of Hong Kong into the LME’s warehouse network opens new avenues for UK firms to engage with Asia’s commodities markets, particularly in new-energy metals critical to the global energy transition. Our leadership in green finance aligns with the UK’s expertise in sustainable investments, creating opportunities for joint ventures in ESG funds, carbon trading, and green fintech. In fintech, Hong Kong’s progressive DA regulations complement the UK’s advancements in digital finance, paving the way for collaborative innovation in areas like blockchain, AI, and stablecoins.
 
     By leveraging Hong Kong’s strengths in extending our financial value chain, embracing new finance, and enhancing global and Mainland connectivity, we invite UK businesses to partner with us in tapping Asia’s growth opportunities. Our shared commitment to innovation, sustainability, and global connectivity positions us to build a future of mutual prosperity.
 
Conclusion
 
     Ladies and gentlemen, Hong Kong stands at the forefront of global finance, driven by our commitment to the 3Es: Extending our financial value chain across equities, fixed income, currencies, and commodities; Embracing fintech and green finance; and Enhancing opportunities for Chinese and international businesses. Our unique position under “one country, two systems,” robust regulatory framework, and vibrant markets make Hong Kong the ideal partner for the UK in navigating Asia’s dynamic markets.
 
     I express my heartfelt gratitude to the Hong Kong Association for hosting this luncheon and for your unwavering commitment to strengthening Hong Kong-UK ties. Let us seize this opportunity to deepen our financial partnership, fostering innovation, sustainability, and prosperity for our shared future. Together, we can shape a world of opportunity, leveraging Hong Kong’s strengths and the UK’s global leadership to drive transformative growth.
 
     Thank you.
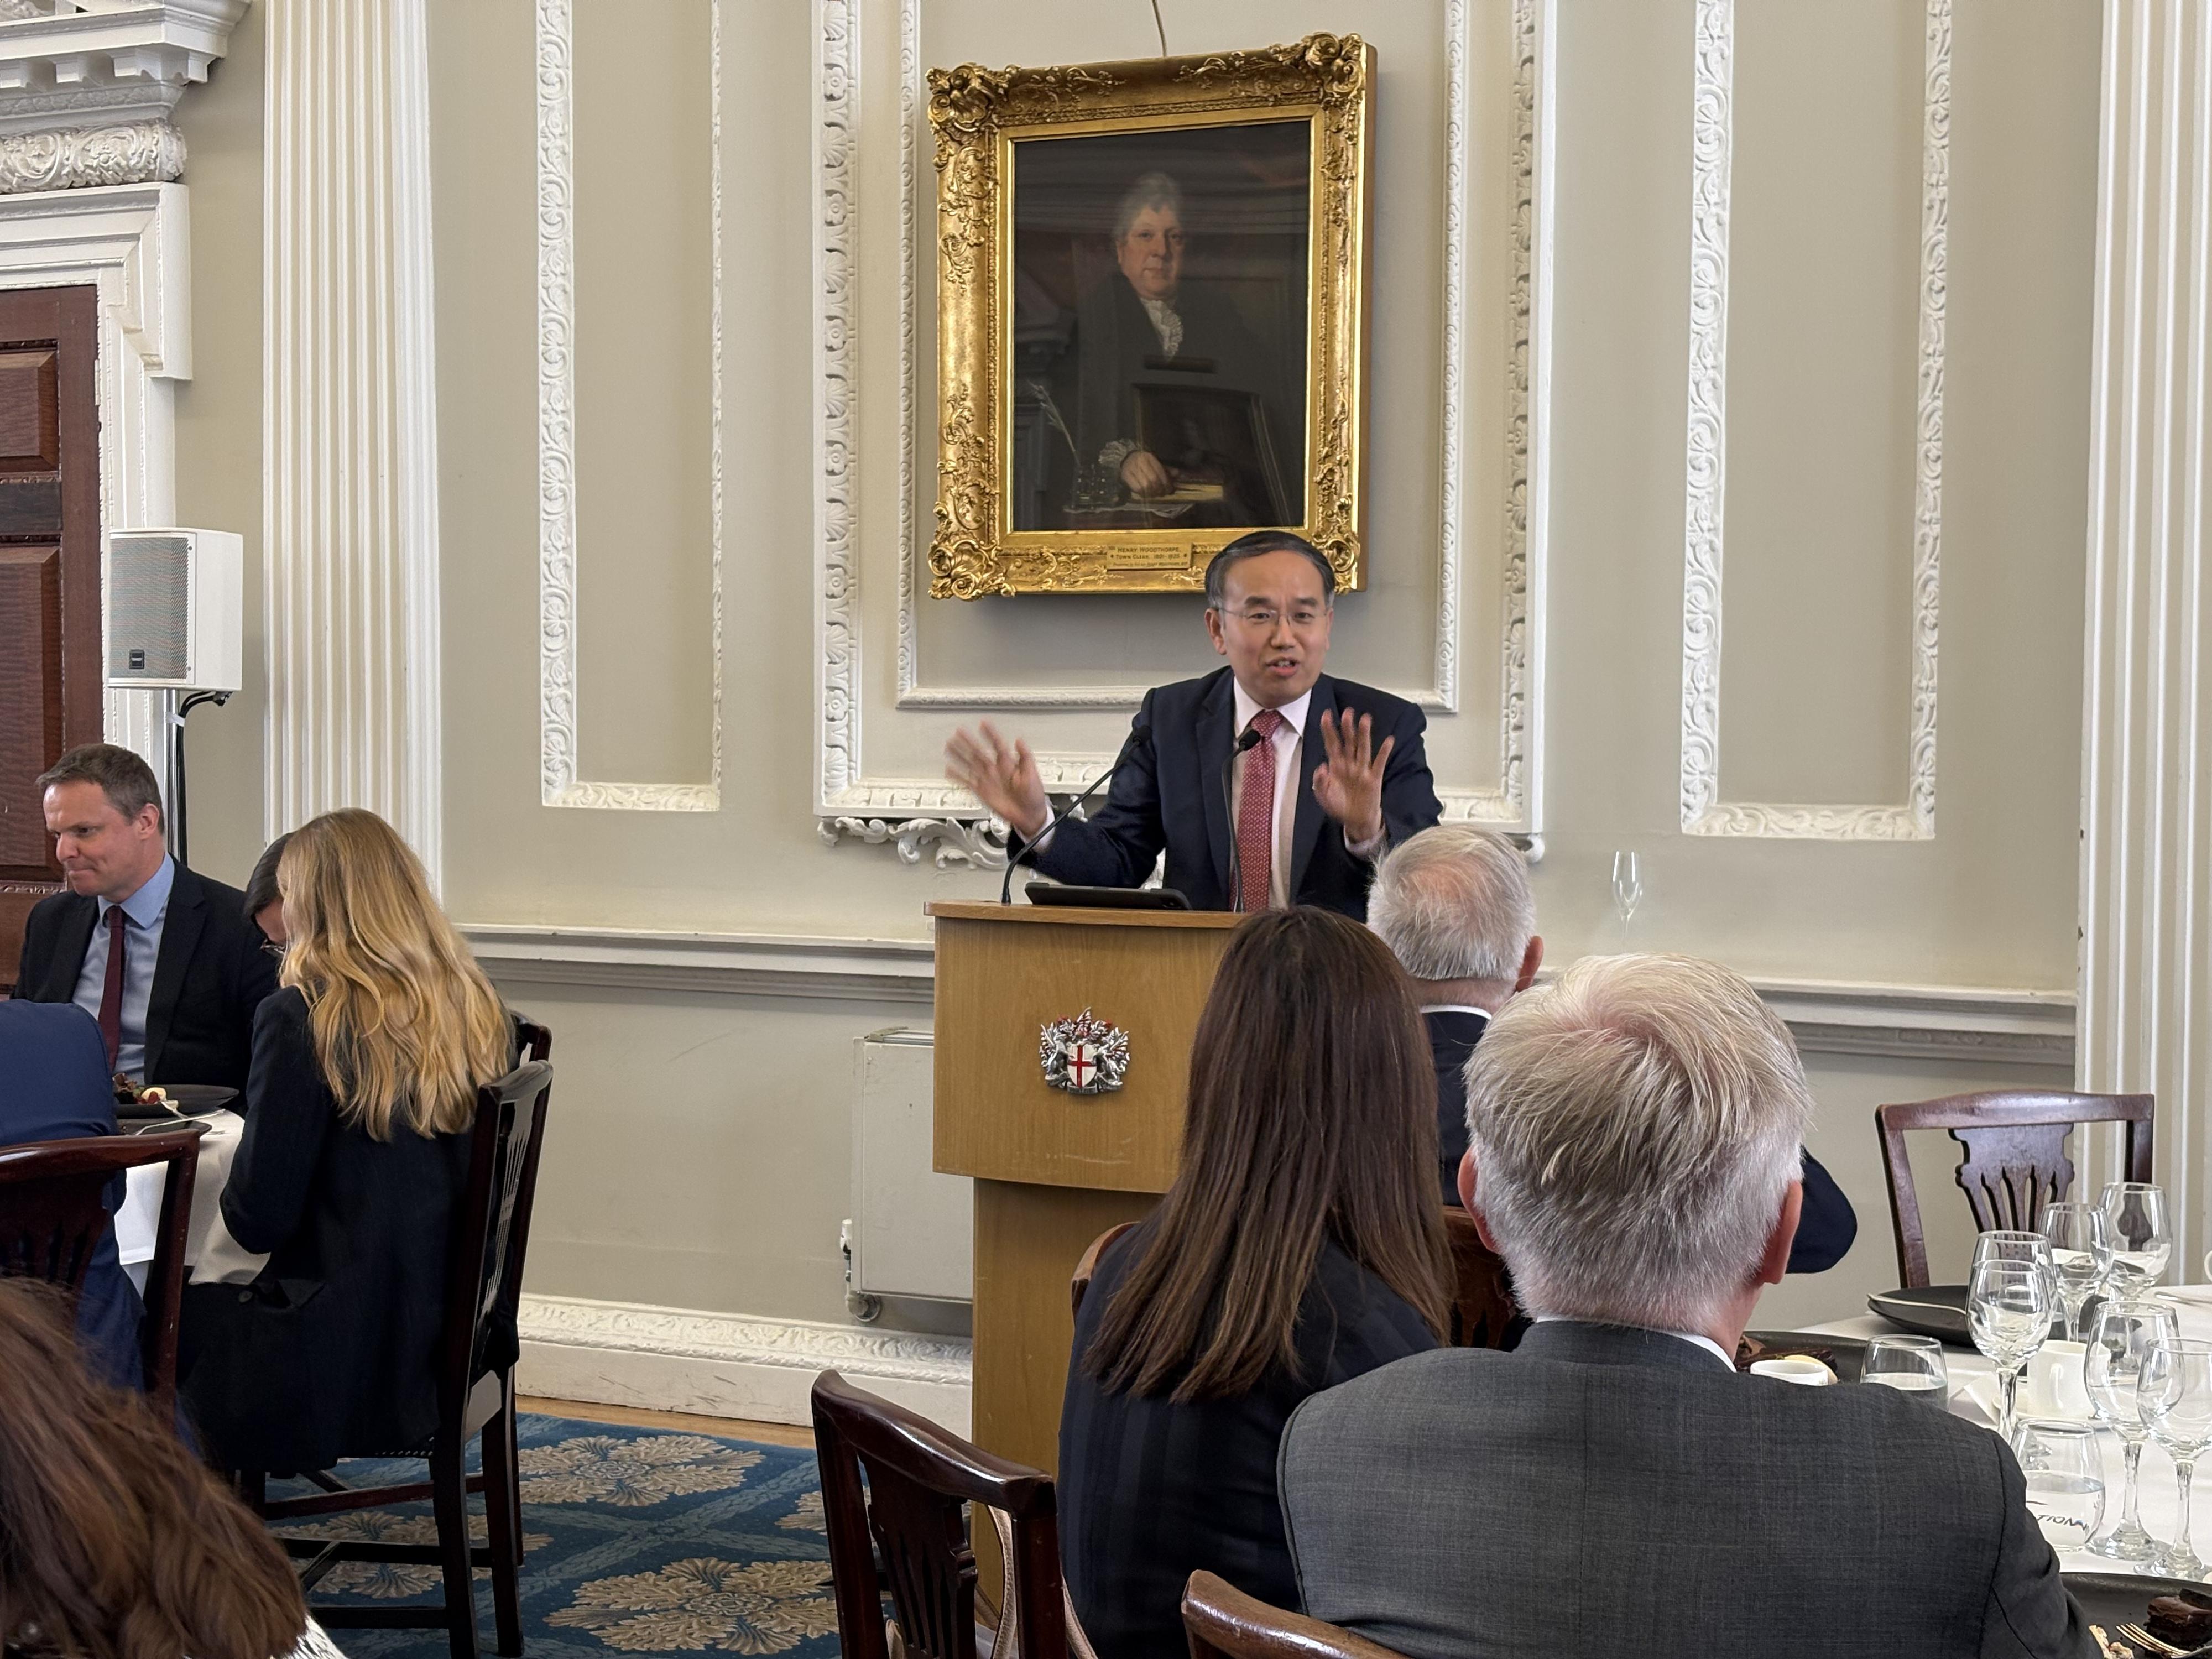
Photo  Photo  
read more

SFST showcases to UK community Hong Kong’s determination to expand international financial co-operation (with photos)

     The Secretary for Financial Services and the Treasury, Mr Christopher Hui, said on June 10 (London time) during his visit to London, the United Kingdom (UK), that Hong Kong is at the forefront of global finance and the digital asset revolution. The city shares the same vision and has complementary expertise with the UK, allowing the two places to drive transformative economic growth through partnership in an era of innovation and sustainablity.
      
     Speaking at a luncheon held by the Hong Kong Association of the UK on June 10 (London time), Mr Hui highlighted Hong Kong’s commitment to three key pillars, namely the 3Es that define the city’s strategic vision as a premier international financial centre. The 3Es refer to extending financial value chain across equities, fixed income, currencies and commodities; embracing fintech and green finance; and enhancing opportunities for Chinese and international businesses.
      
     He said Hong Kong’s ability to offer a diversified, resilient and innovative financial ecosystem and the Government’s determination to extend the financial value chain are creating a robust development platform that serves both regional and international markets. The vibrant capital markets in Hong Kong, driven by geopolitical developments and the Mainland’s technological advancements, are also offering global investors, including those from the UK, a gateway and access to invest in Asia’s burgeoning tech sector by leveraging Hong Kong’s deep market liquidity and robust regulatory framework.
      
     While mentioning the UK’s expertise in commodities trading, Mr Hui remarked that Hong Kong’s integration into the London Metal Exchange’s global warehouse network in January this year not only enhances Hong Kong’s commodities infrastructure but also creates significant opportunities for UK firms. Riding on Hong Kong’s proximity to Asia’s industrial markets, Hong Kong can partner with the UK to jointly tap into the growing demand for new-energy metals and support global industrial transformation and sustainable development.
      
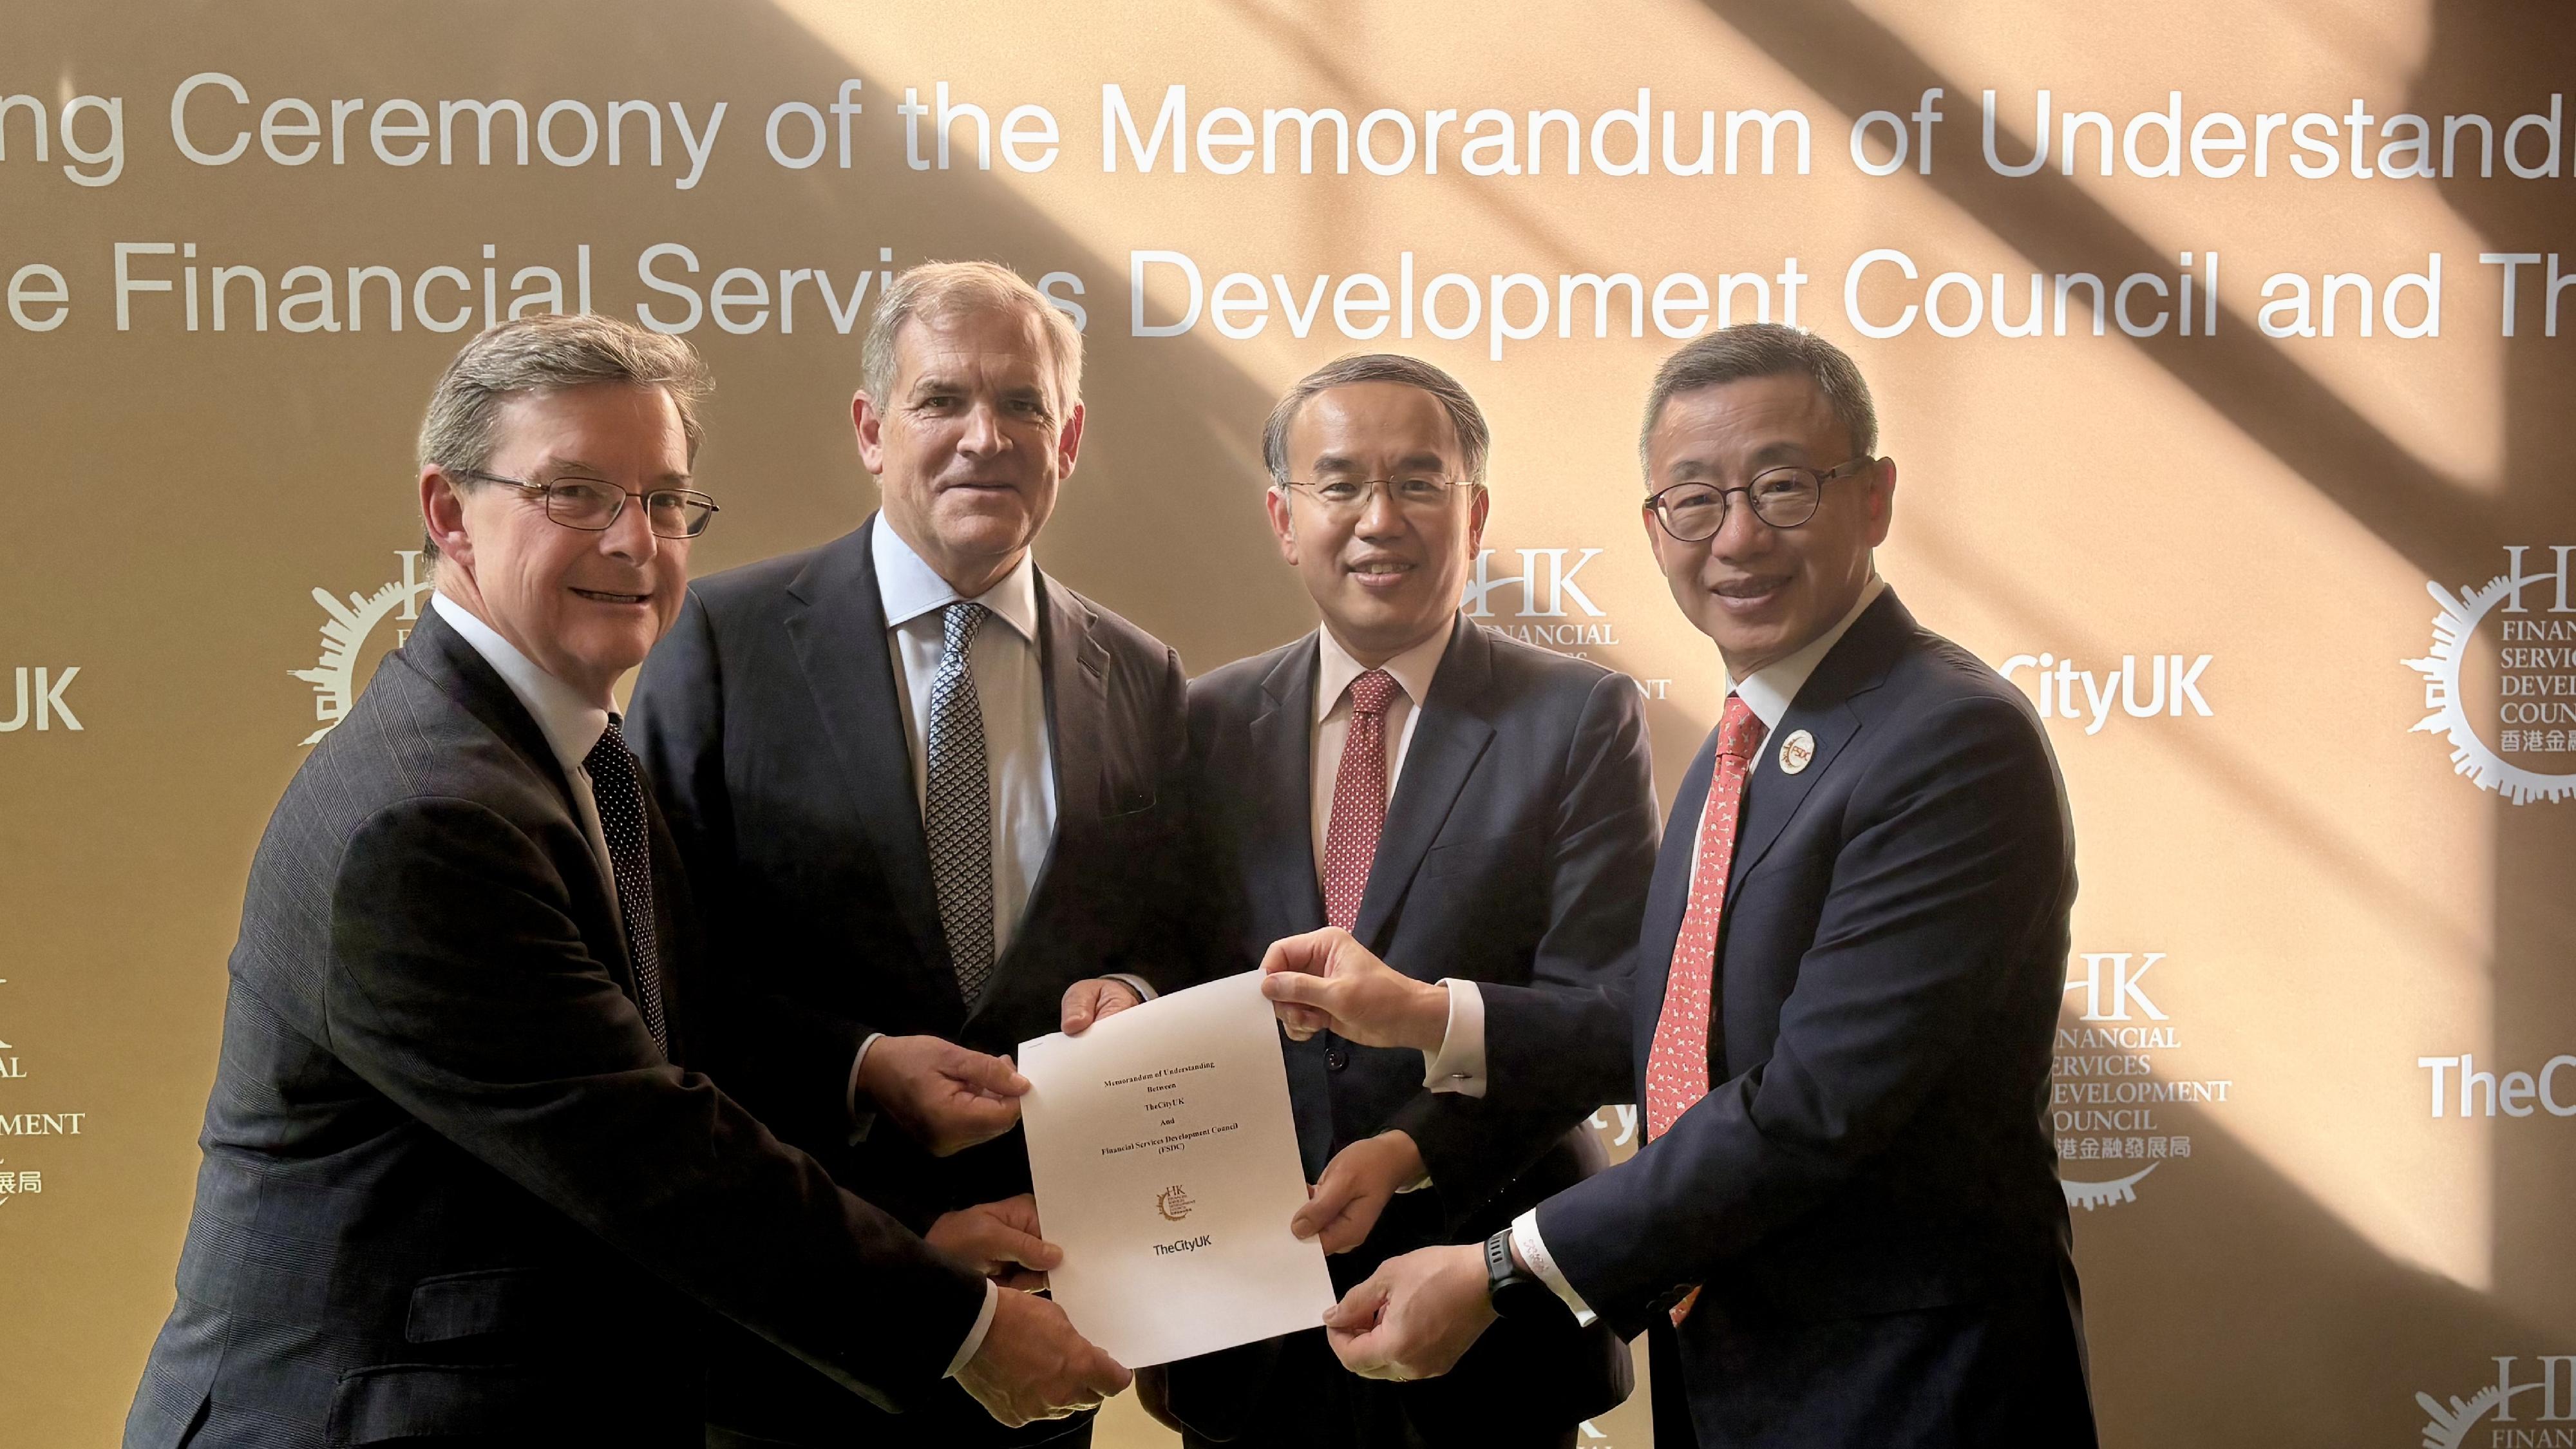
     Among the highlights of the UK leg was the signing of a memorandum of understanding (MOU) between the Financial Services Development Council (FSDC) and TheCityUK to establish a partnership in sharing insights and best practices to advance transition finance, collaborating on workforce development to address evolving market requirements, as well as establishing a framework to conduct an annual review to assess progress in collaboration and explore new opportunities. The MOU was signed by the Executive Director of the FSDC, Dr King Au, and the Managing Director of Public Affairs, Policy and Research of TheCityUK, Mr John Godfrey.
      
     Mr Hui, together with the Leadership Council Chair of TheCityUK, Mr Bruce Carnegie-Brown, witnessed the signing of the MOU on June 10 (London time). Mr Hui said that the MOU reflects a shared vision to harness the strengths of Hong Kong and the UK, creating opportunities that benefit both places and the global financial ecosystem.
      
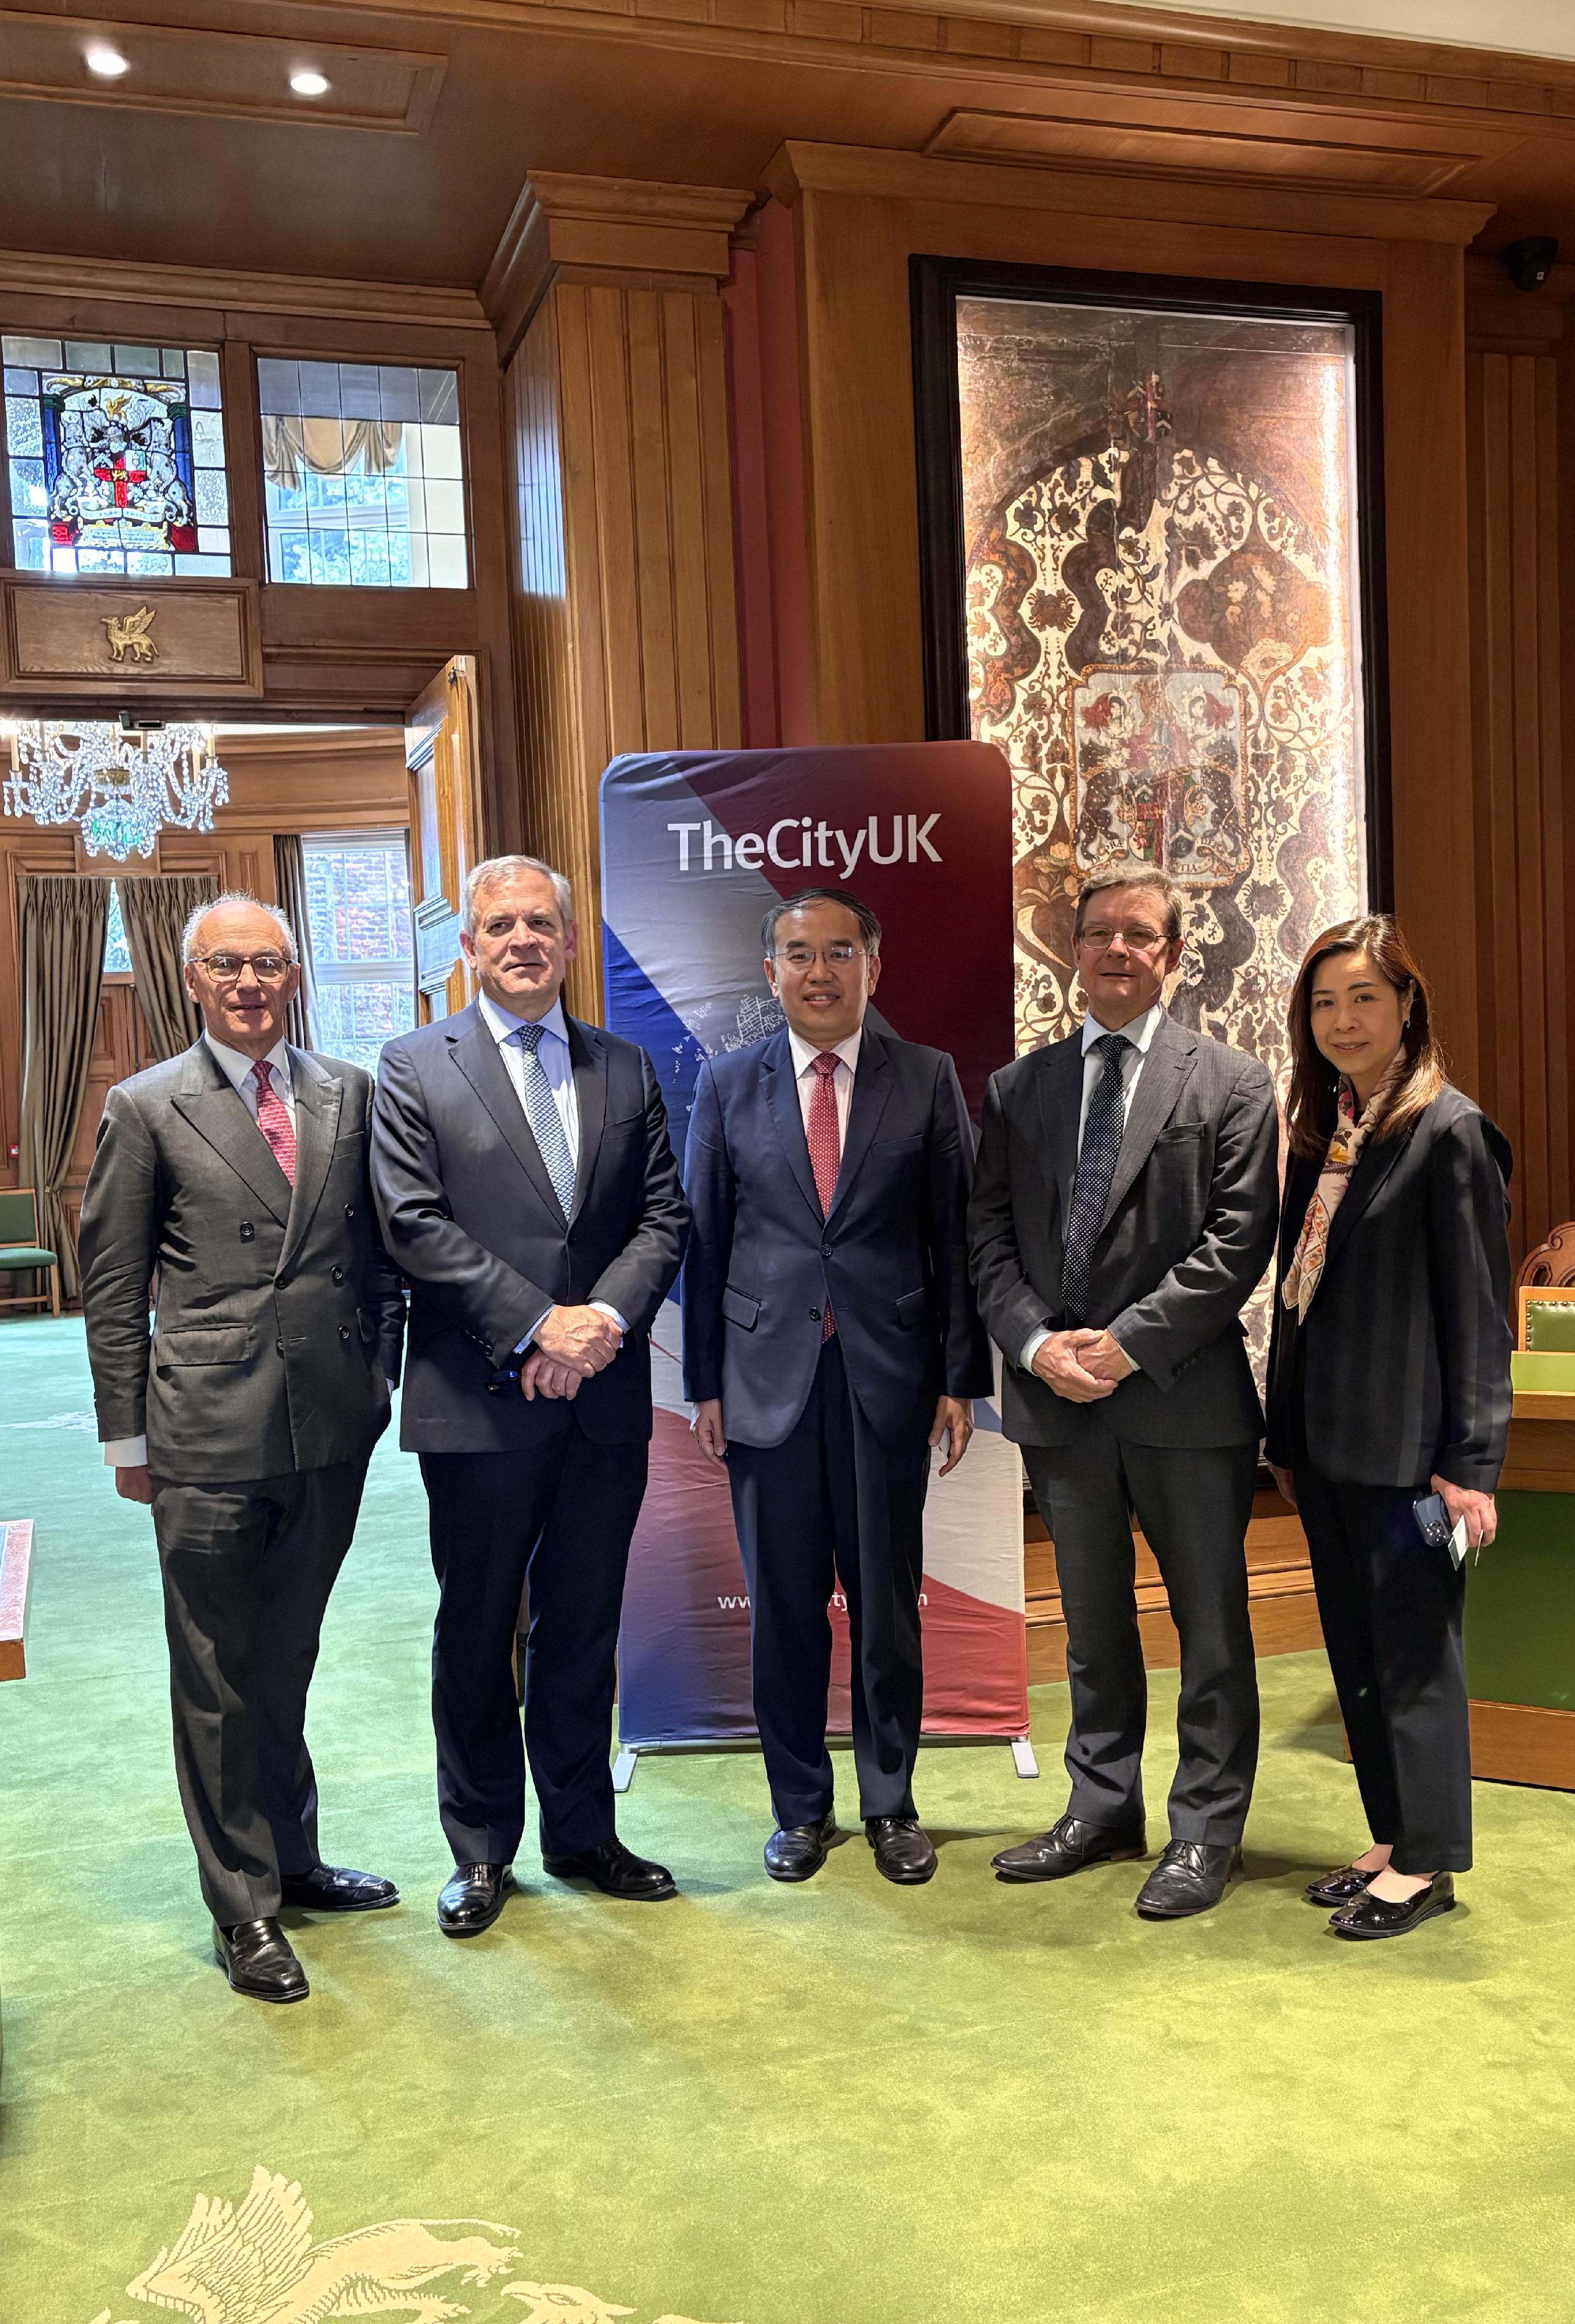
     Prior to the signing ceremony, Mr Hui had a roundtable meeting with members of the TheCityUK, which represents an industry contributing over 12 per cent of the UK’s economic output and employing nearly 2.5 million people in financial and related professions. Mr Hui said that investors nowadays are gravitating towards markets that provide clarity, consistency and credibility, which are qualities that Hong Kong embodies in abundance. Moreover, Hong Kong continues to uphold the mission of striking a balance between innovation and investor protection through its regulatory framework in the process of integrating traditional financial services with innovative digital asset technologies for facilitating real economy activities. All in all, Hong Kong is an ideal partner for the UK to work with in unlocking horizons for growth and prosperity, especially in areas of wealth management and digital assets.
      
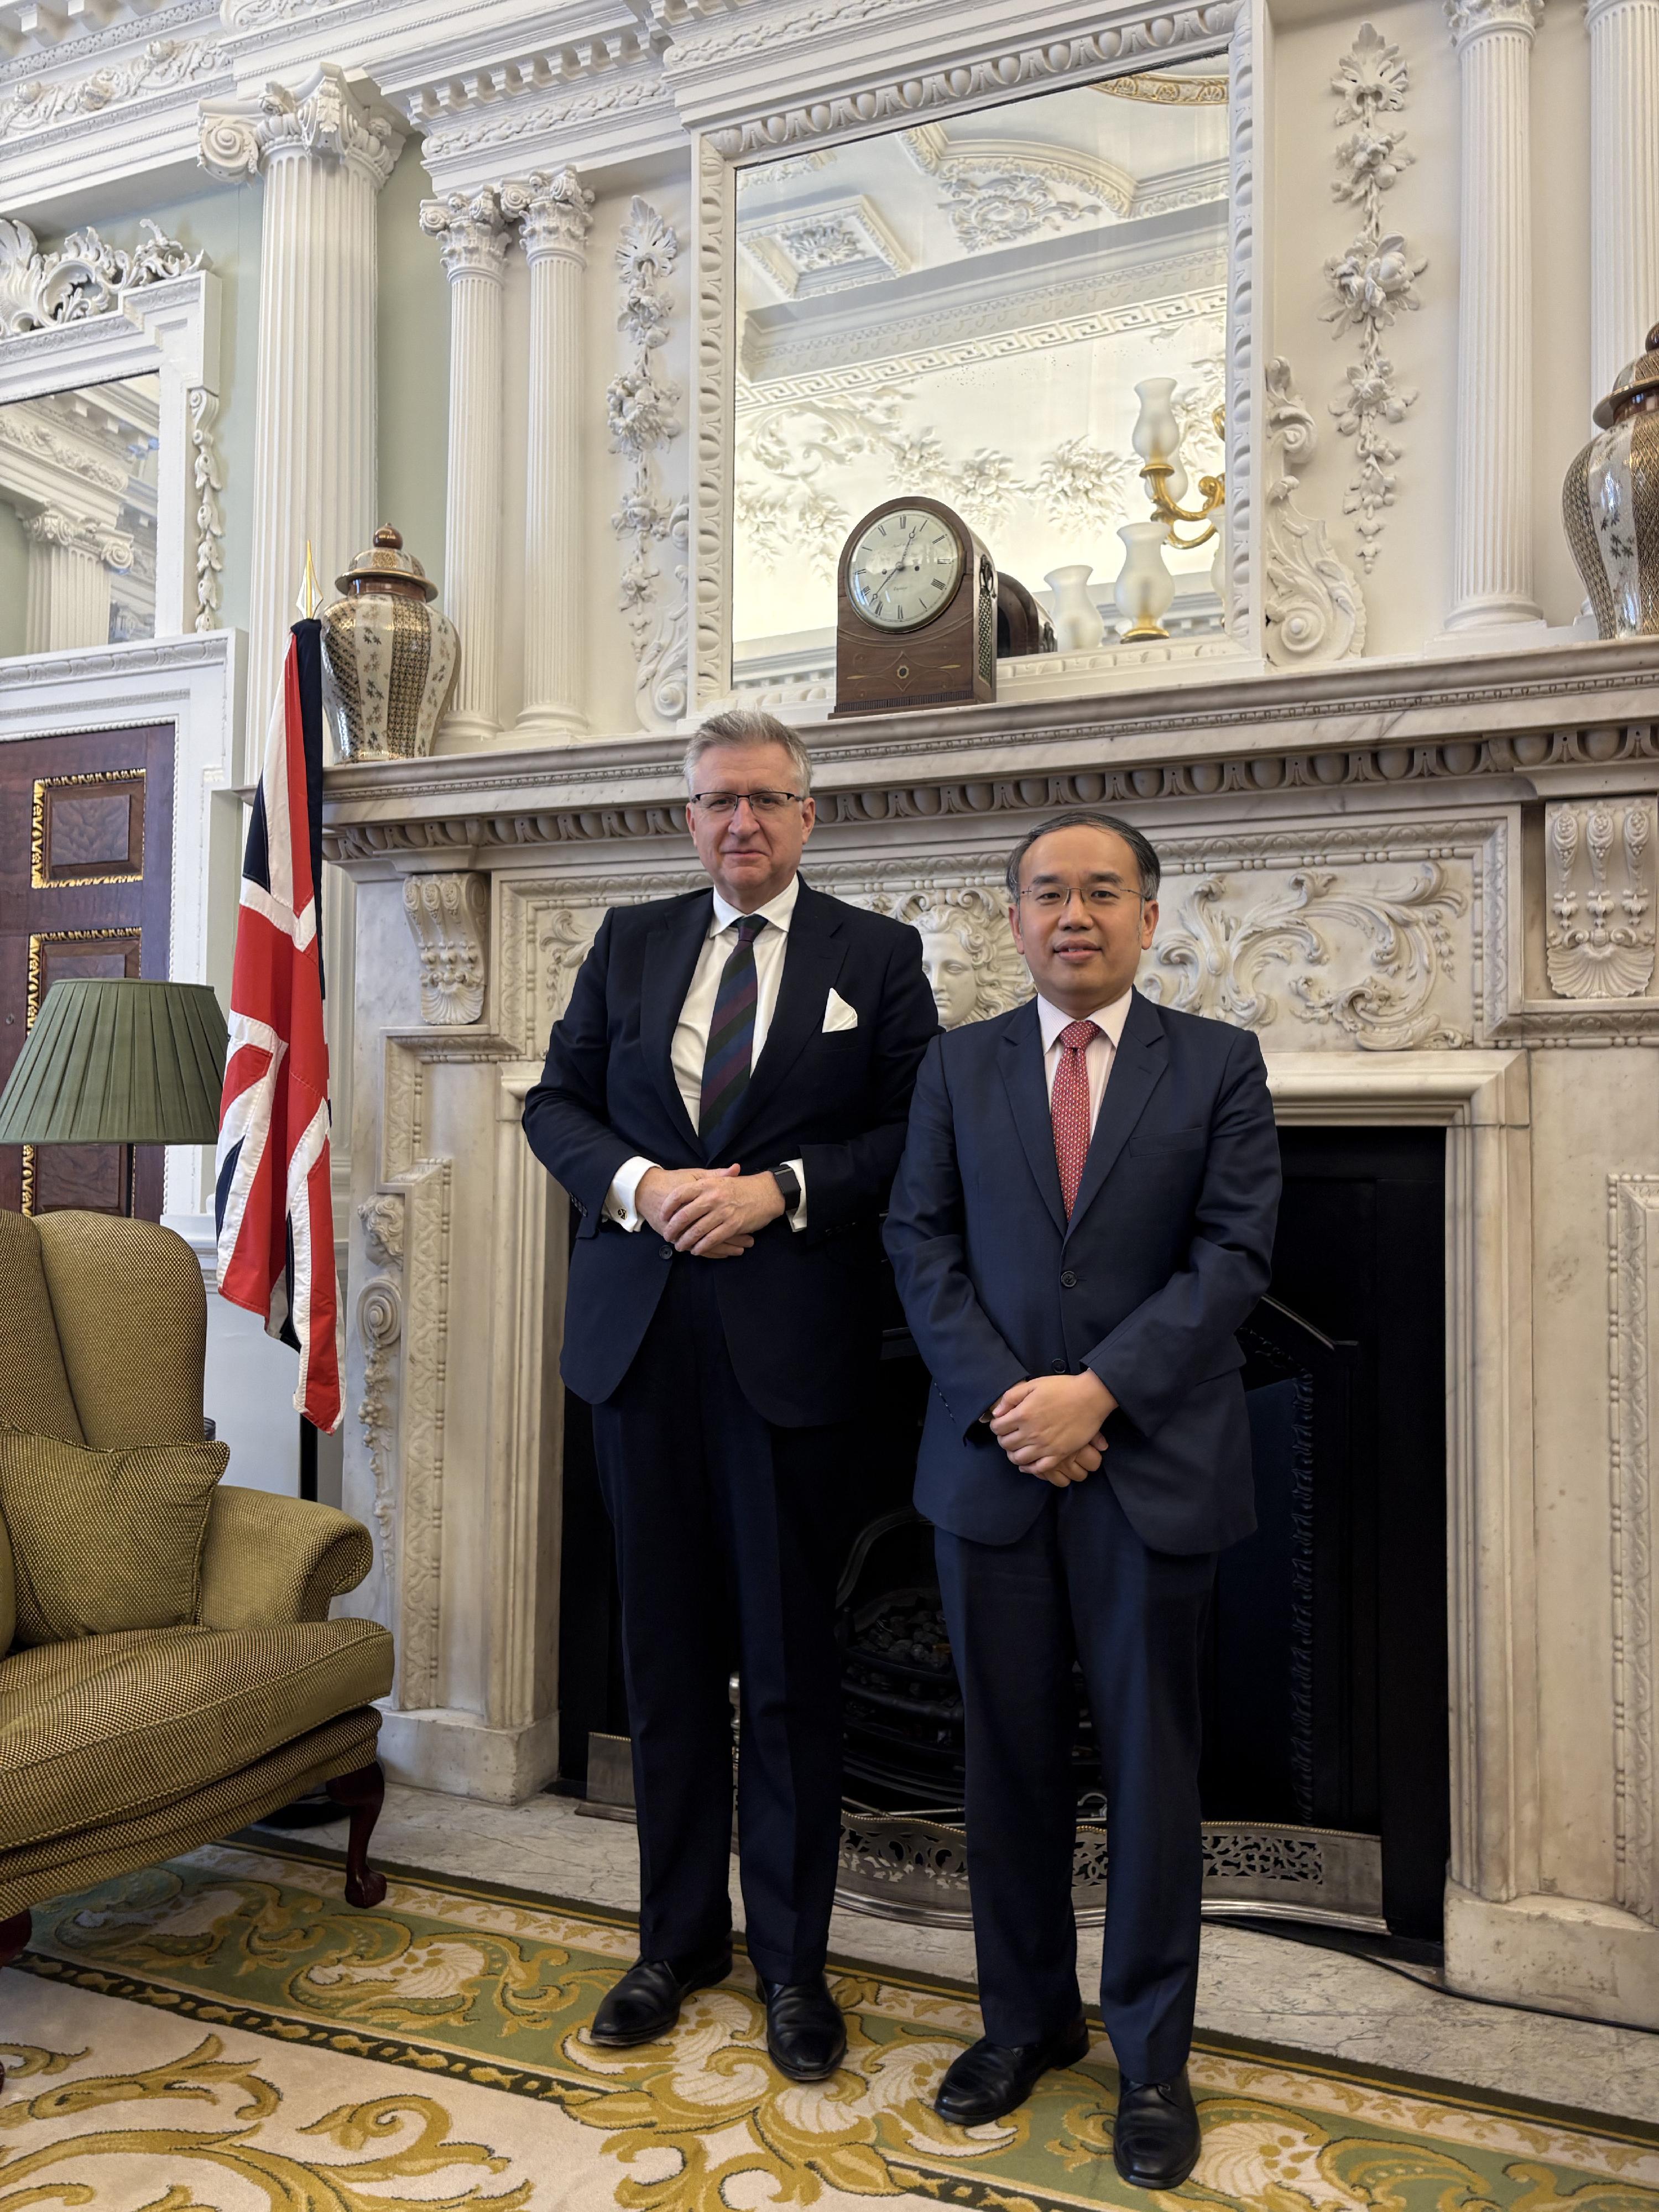
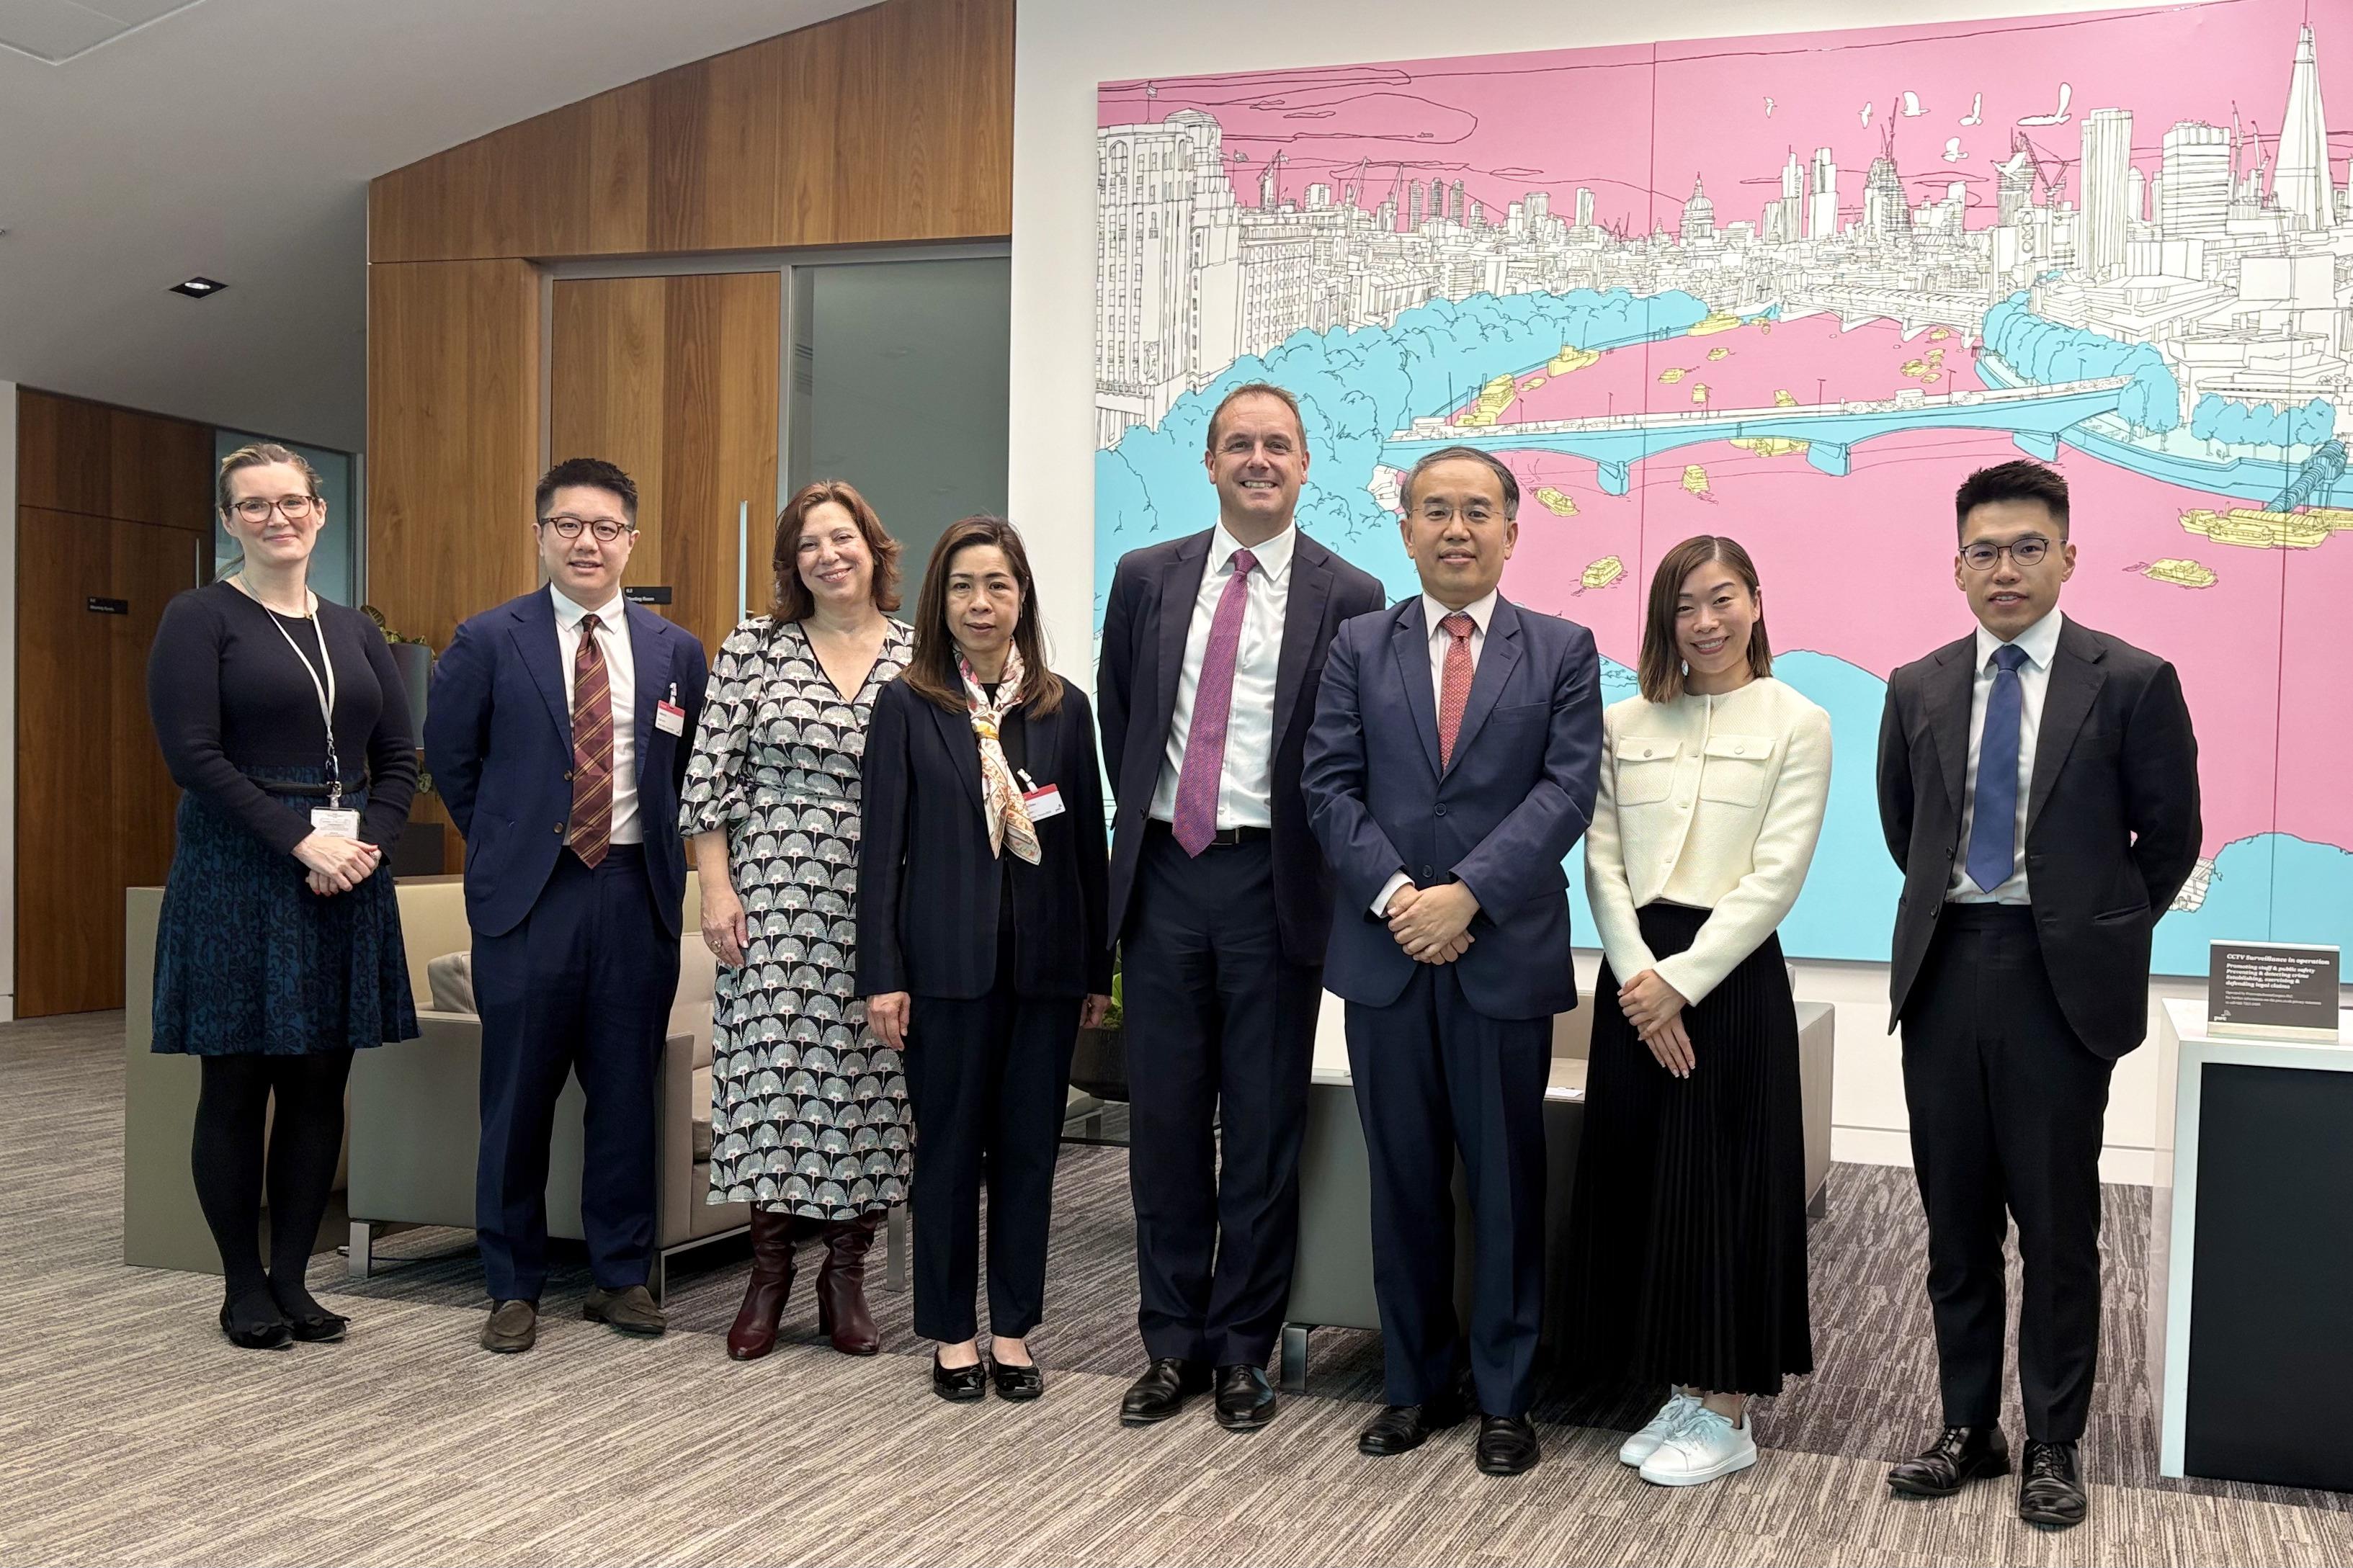
     Earlier in the day, Mr Hui had a bilateral meeting with the Lord Mayor of the City of London, Mr Alderman Alastair King, to update him on Hong Kong’s latest developments on the financial services front, which benefit from the unique convergence of global and Mainland advantages. He also met with the Chief Markets Officer of PwC UK, Mr Carl Sizer, to discuss the role the auditing and accounting profession can play to support Mainland enterprises going global.
      
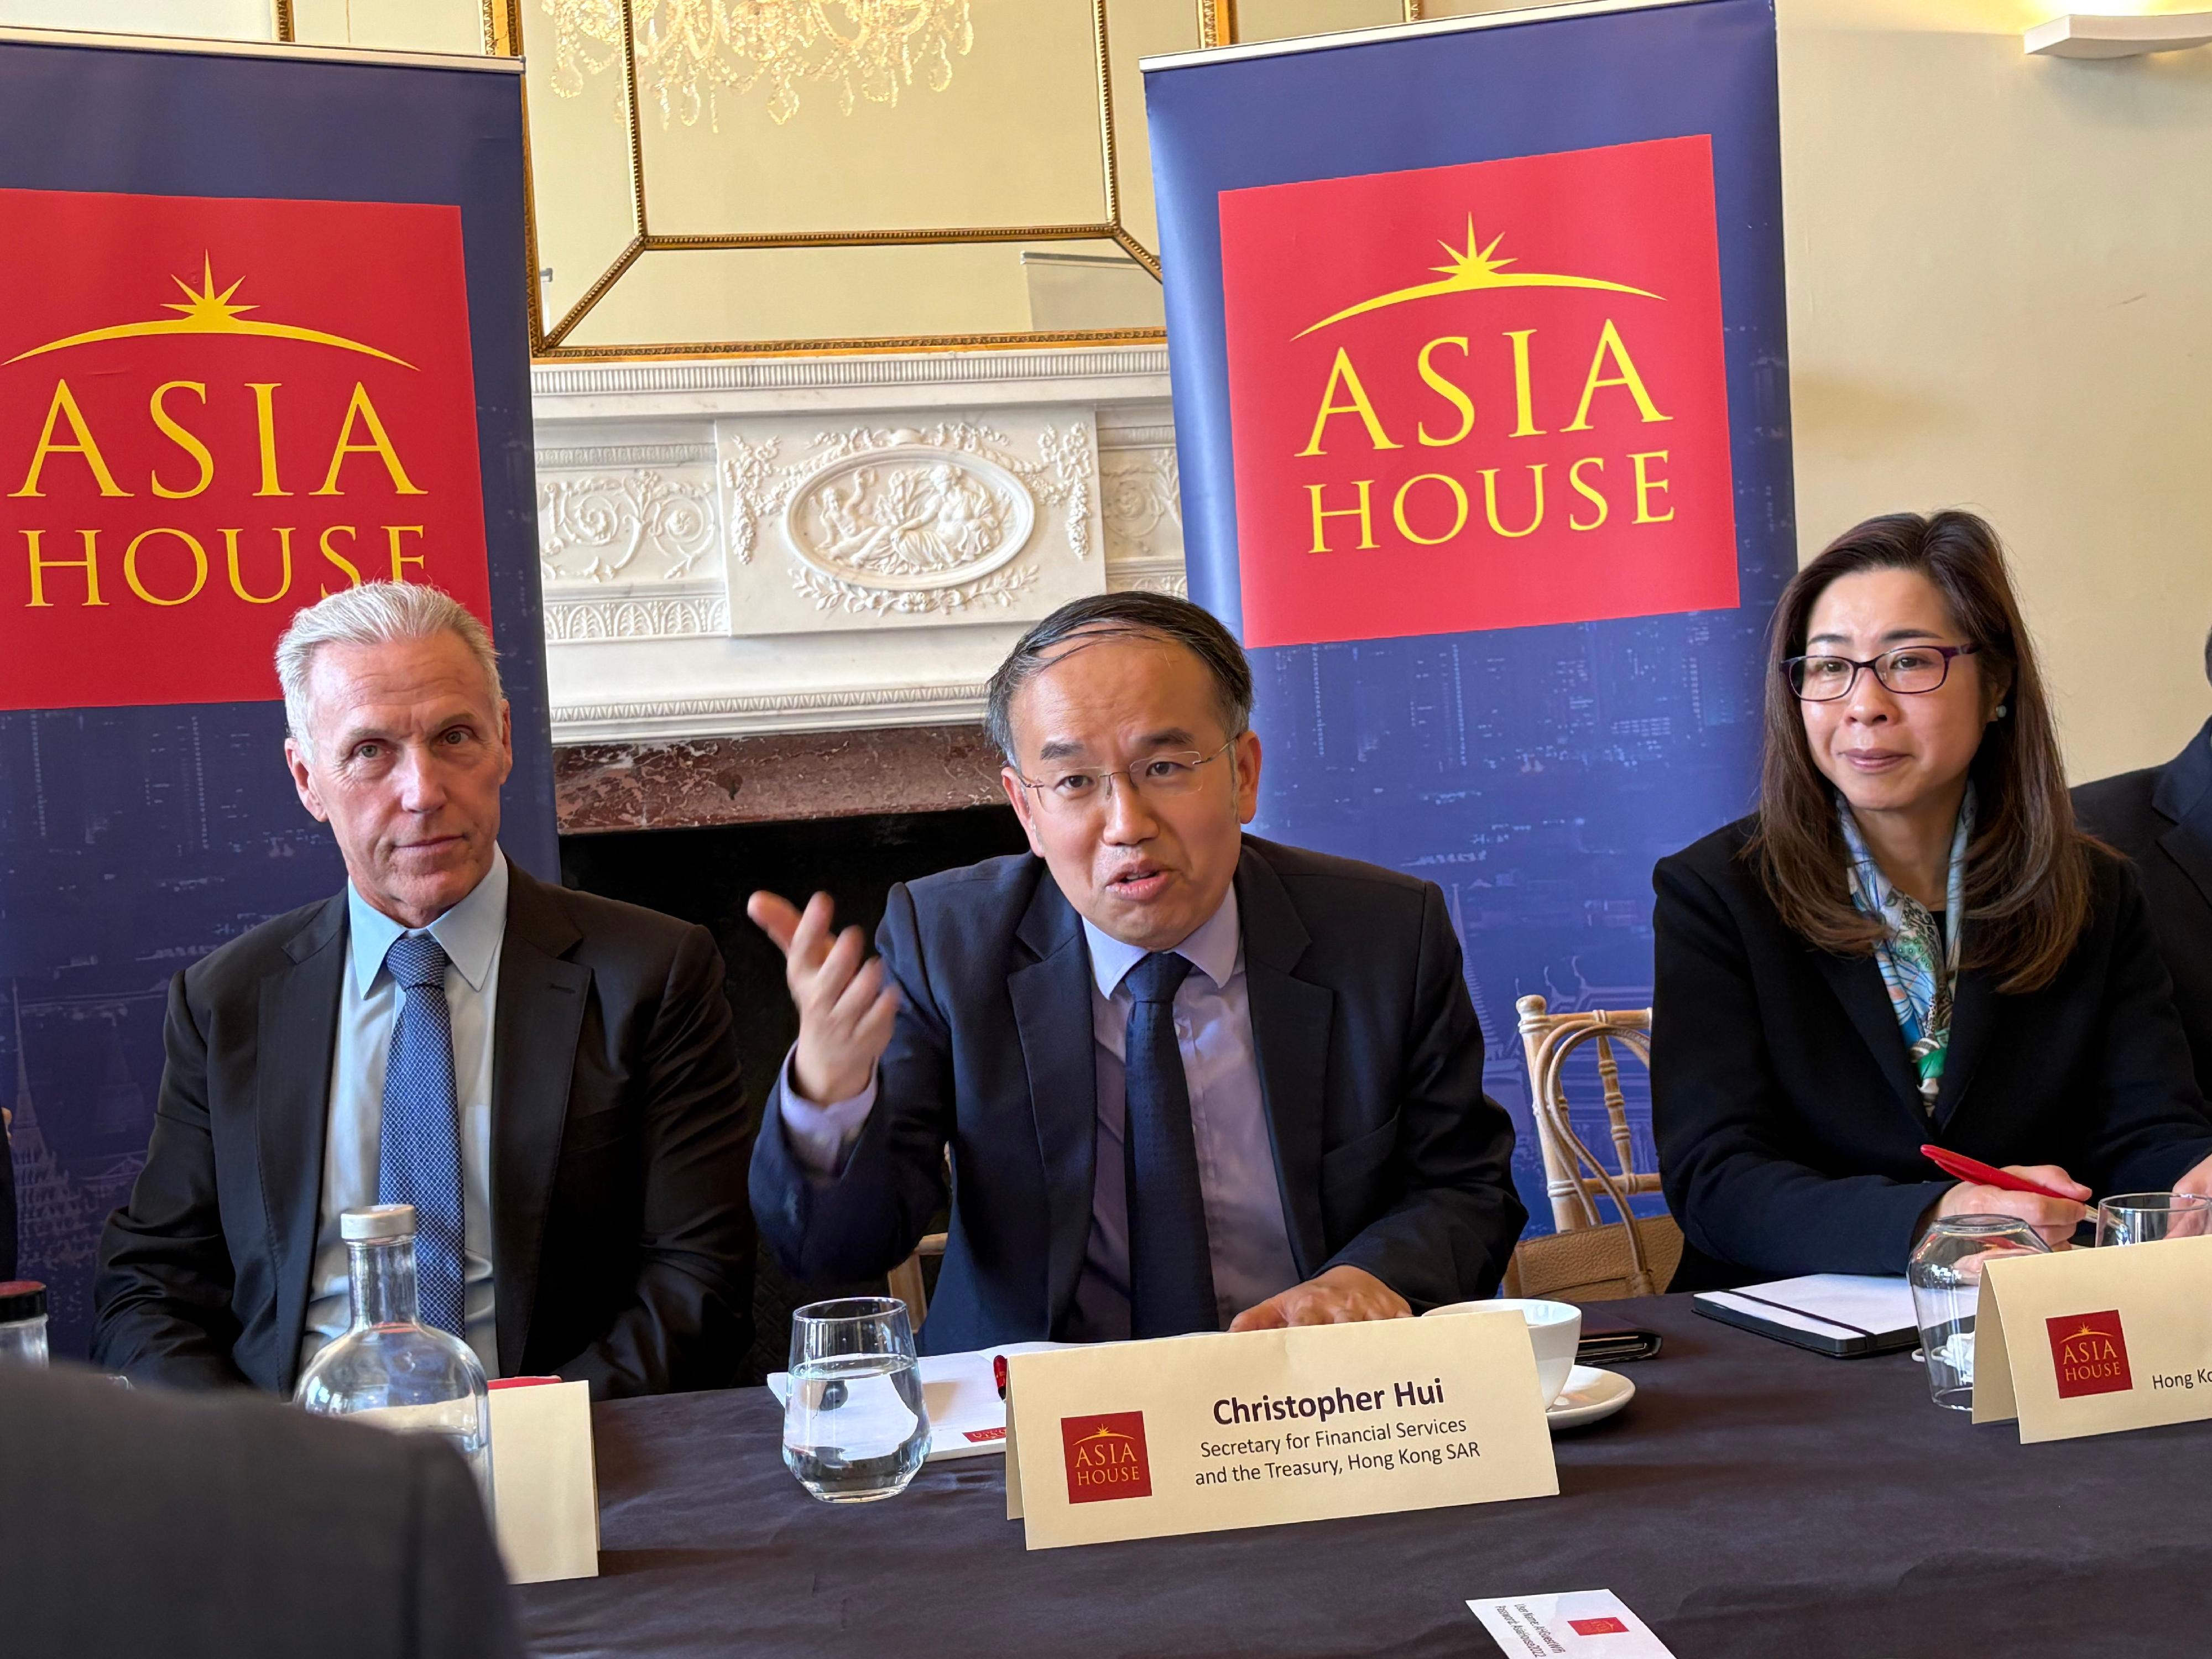
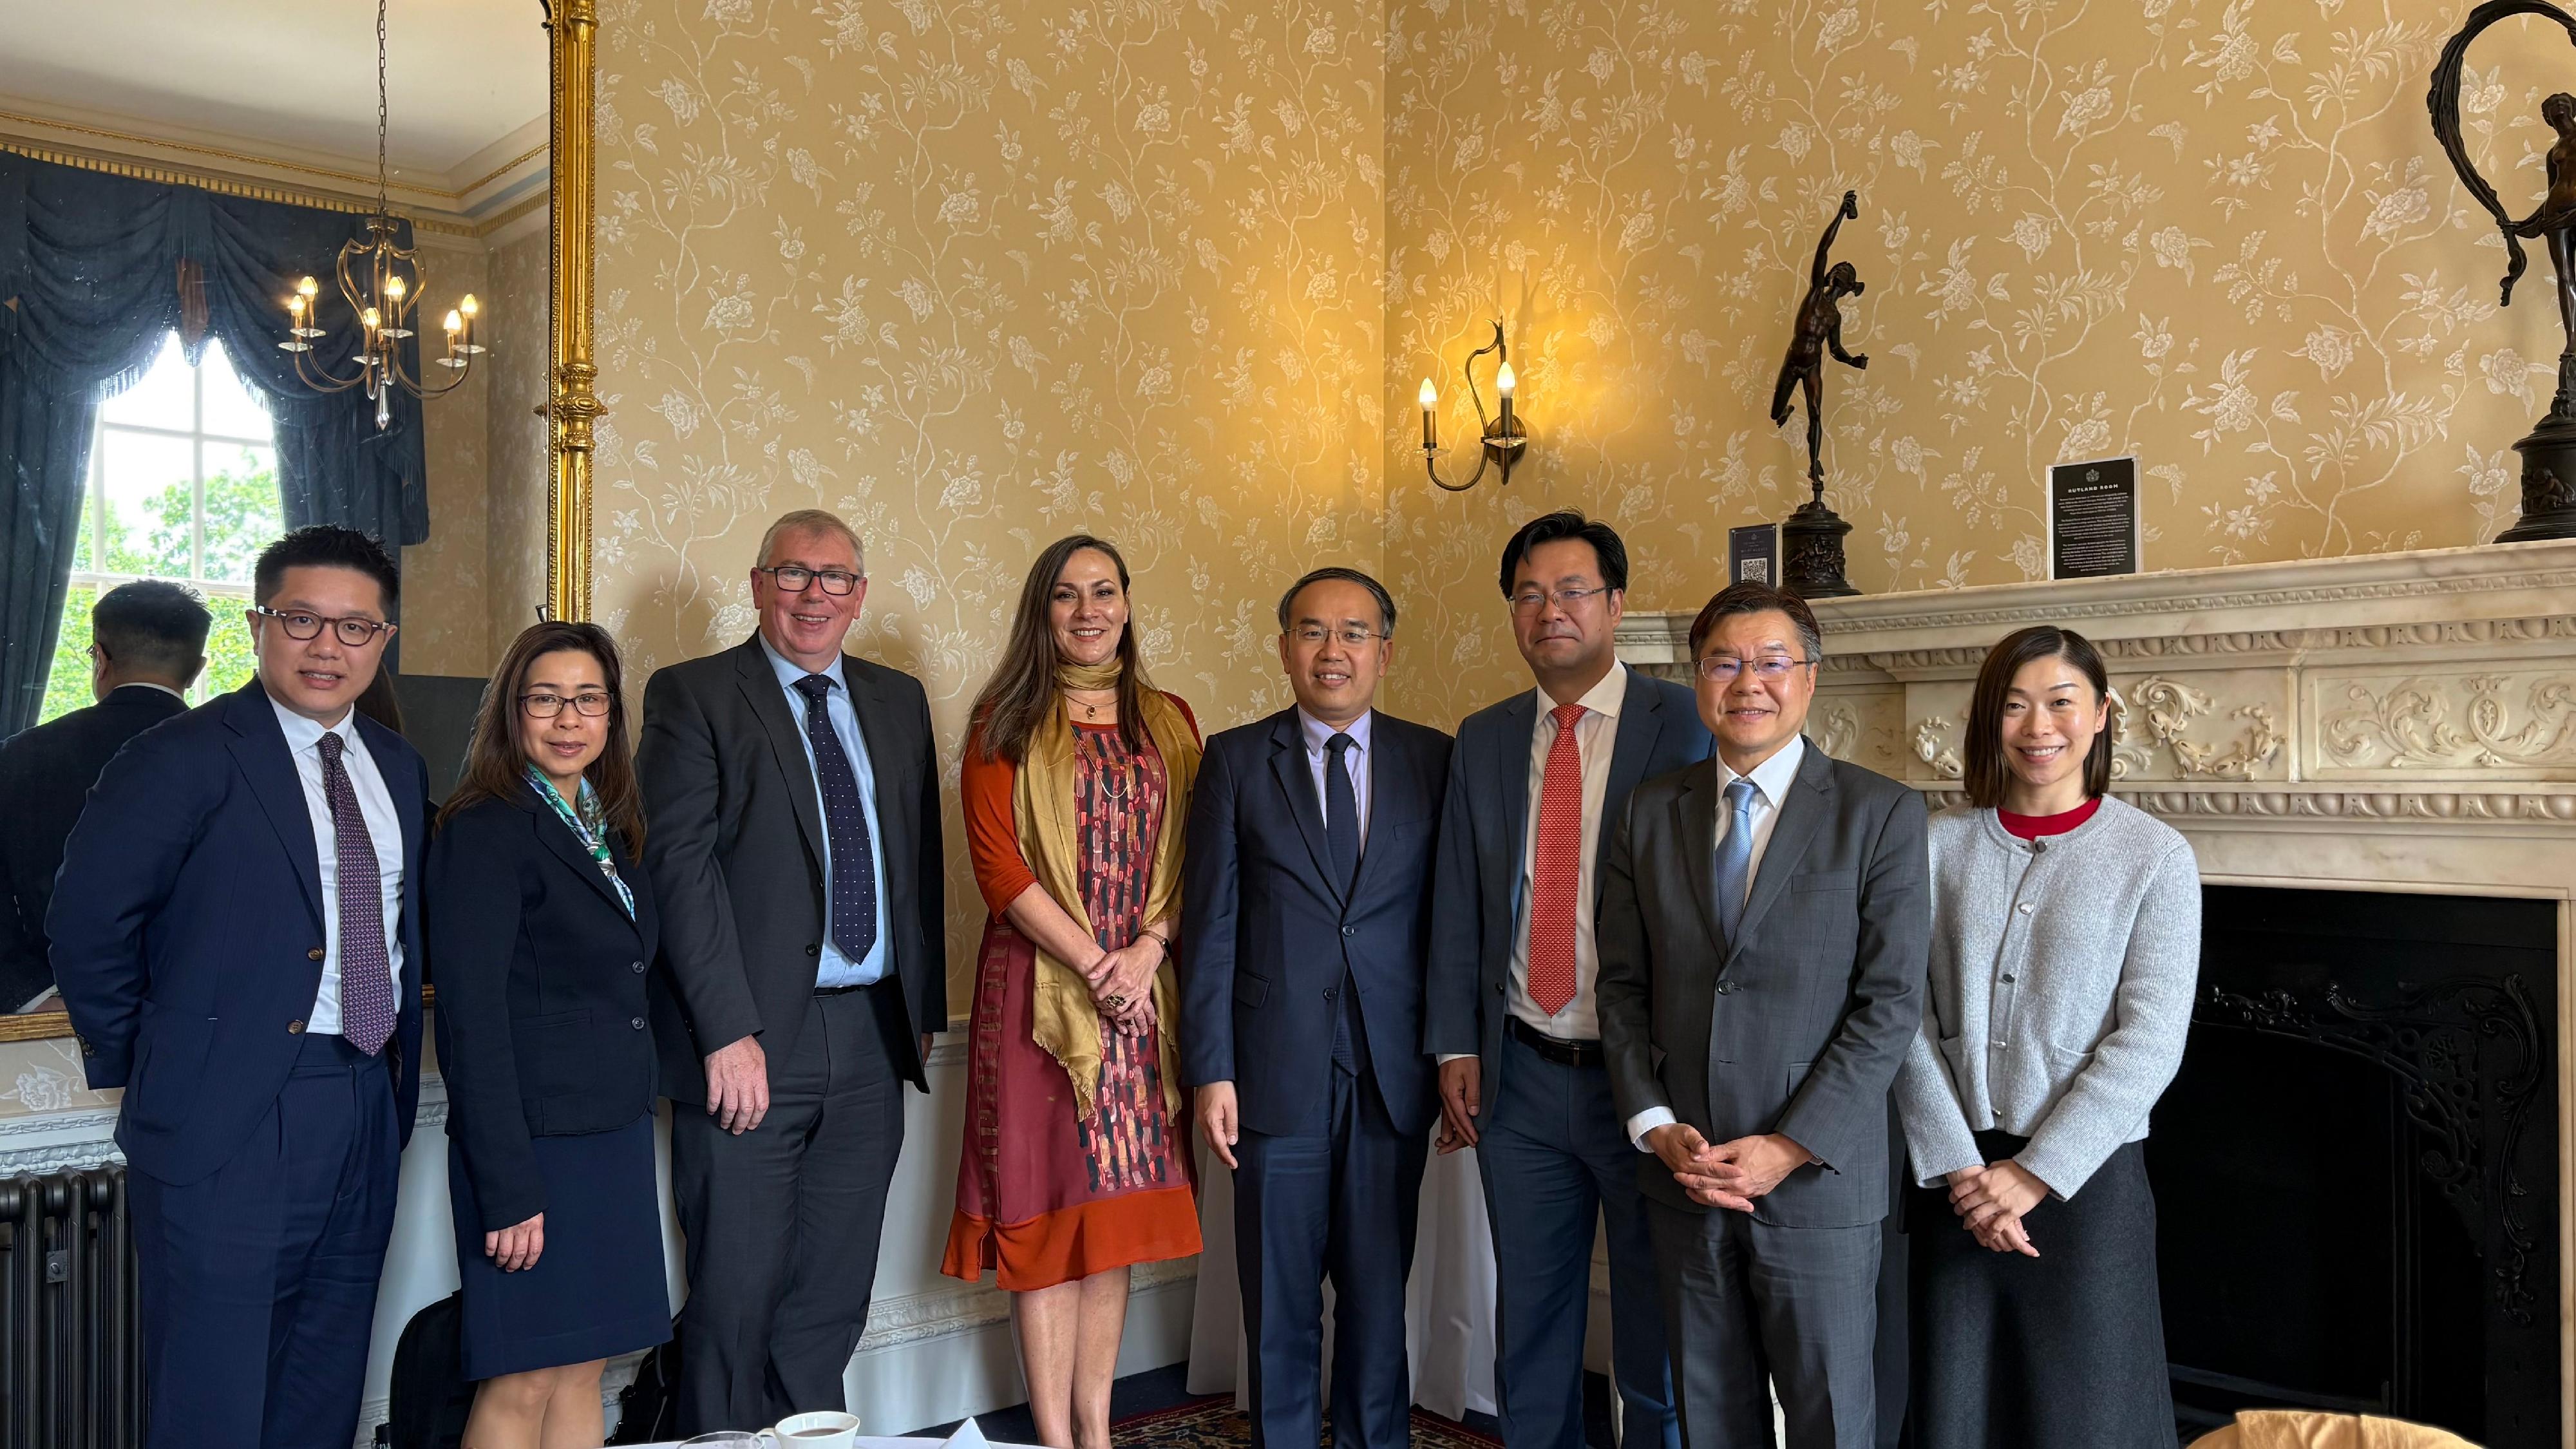
     In the morning of June 9 (London time), Mr Hui attended a members briefing of a British independent think-tank, Asia House, to enlighten its members on the latest financial developments of Hong Kong as well as the Greater Bay Area at large. In a Q&A session moderated by the Chief Executive of Asia House, Mr Michael Lawrence, Mr Hui responded to members’ questions about Hong Kong’s financial outlook. The members were particularly interested in Hong Kong’s connectivity with international markets and the city’s fintech development.
      
     Mr Hui told the members that Hong Kong has been experiencing a flourishing financial market amid the challenging global financial landscape. The securities market of Hong Kong recorded an average daily turnover of US$31 billion for the first five months of 2025, a year-on-year increase of 120 per cent. The Government is also taking bold moves to boost fintech development, such as introducing the Stablecoins Ordinance which is scheduled to be enacted this August.
      
     During a lunch meeting with representatives of the ICBC Standard Bank on the same day, Mr Hui introduced to its Chief Executive Officer, Mr Wang Wenbin, and other senior management, the international gold trading market and commodity trading ecosystem that Hong Kong is shaping. Both parties had a very productive discussion about the vast potential that Hong Kong may bring about. The bank serves as a global banking platform for commodities, fixed income and currency products for clients.
      
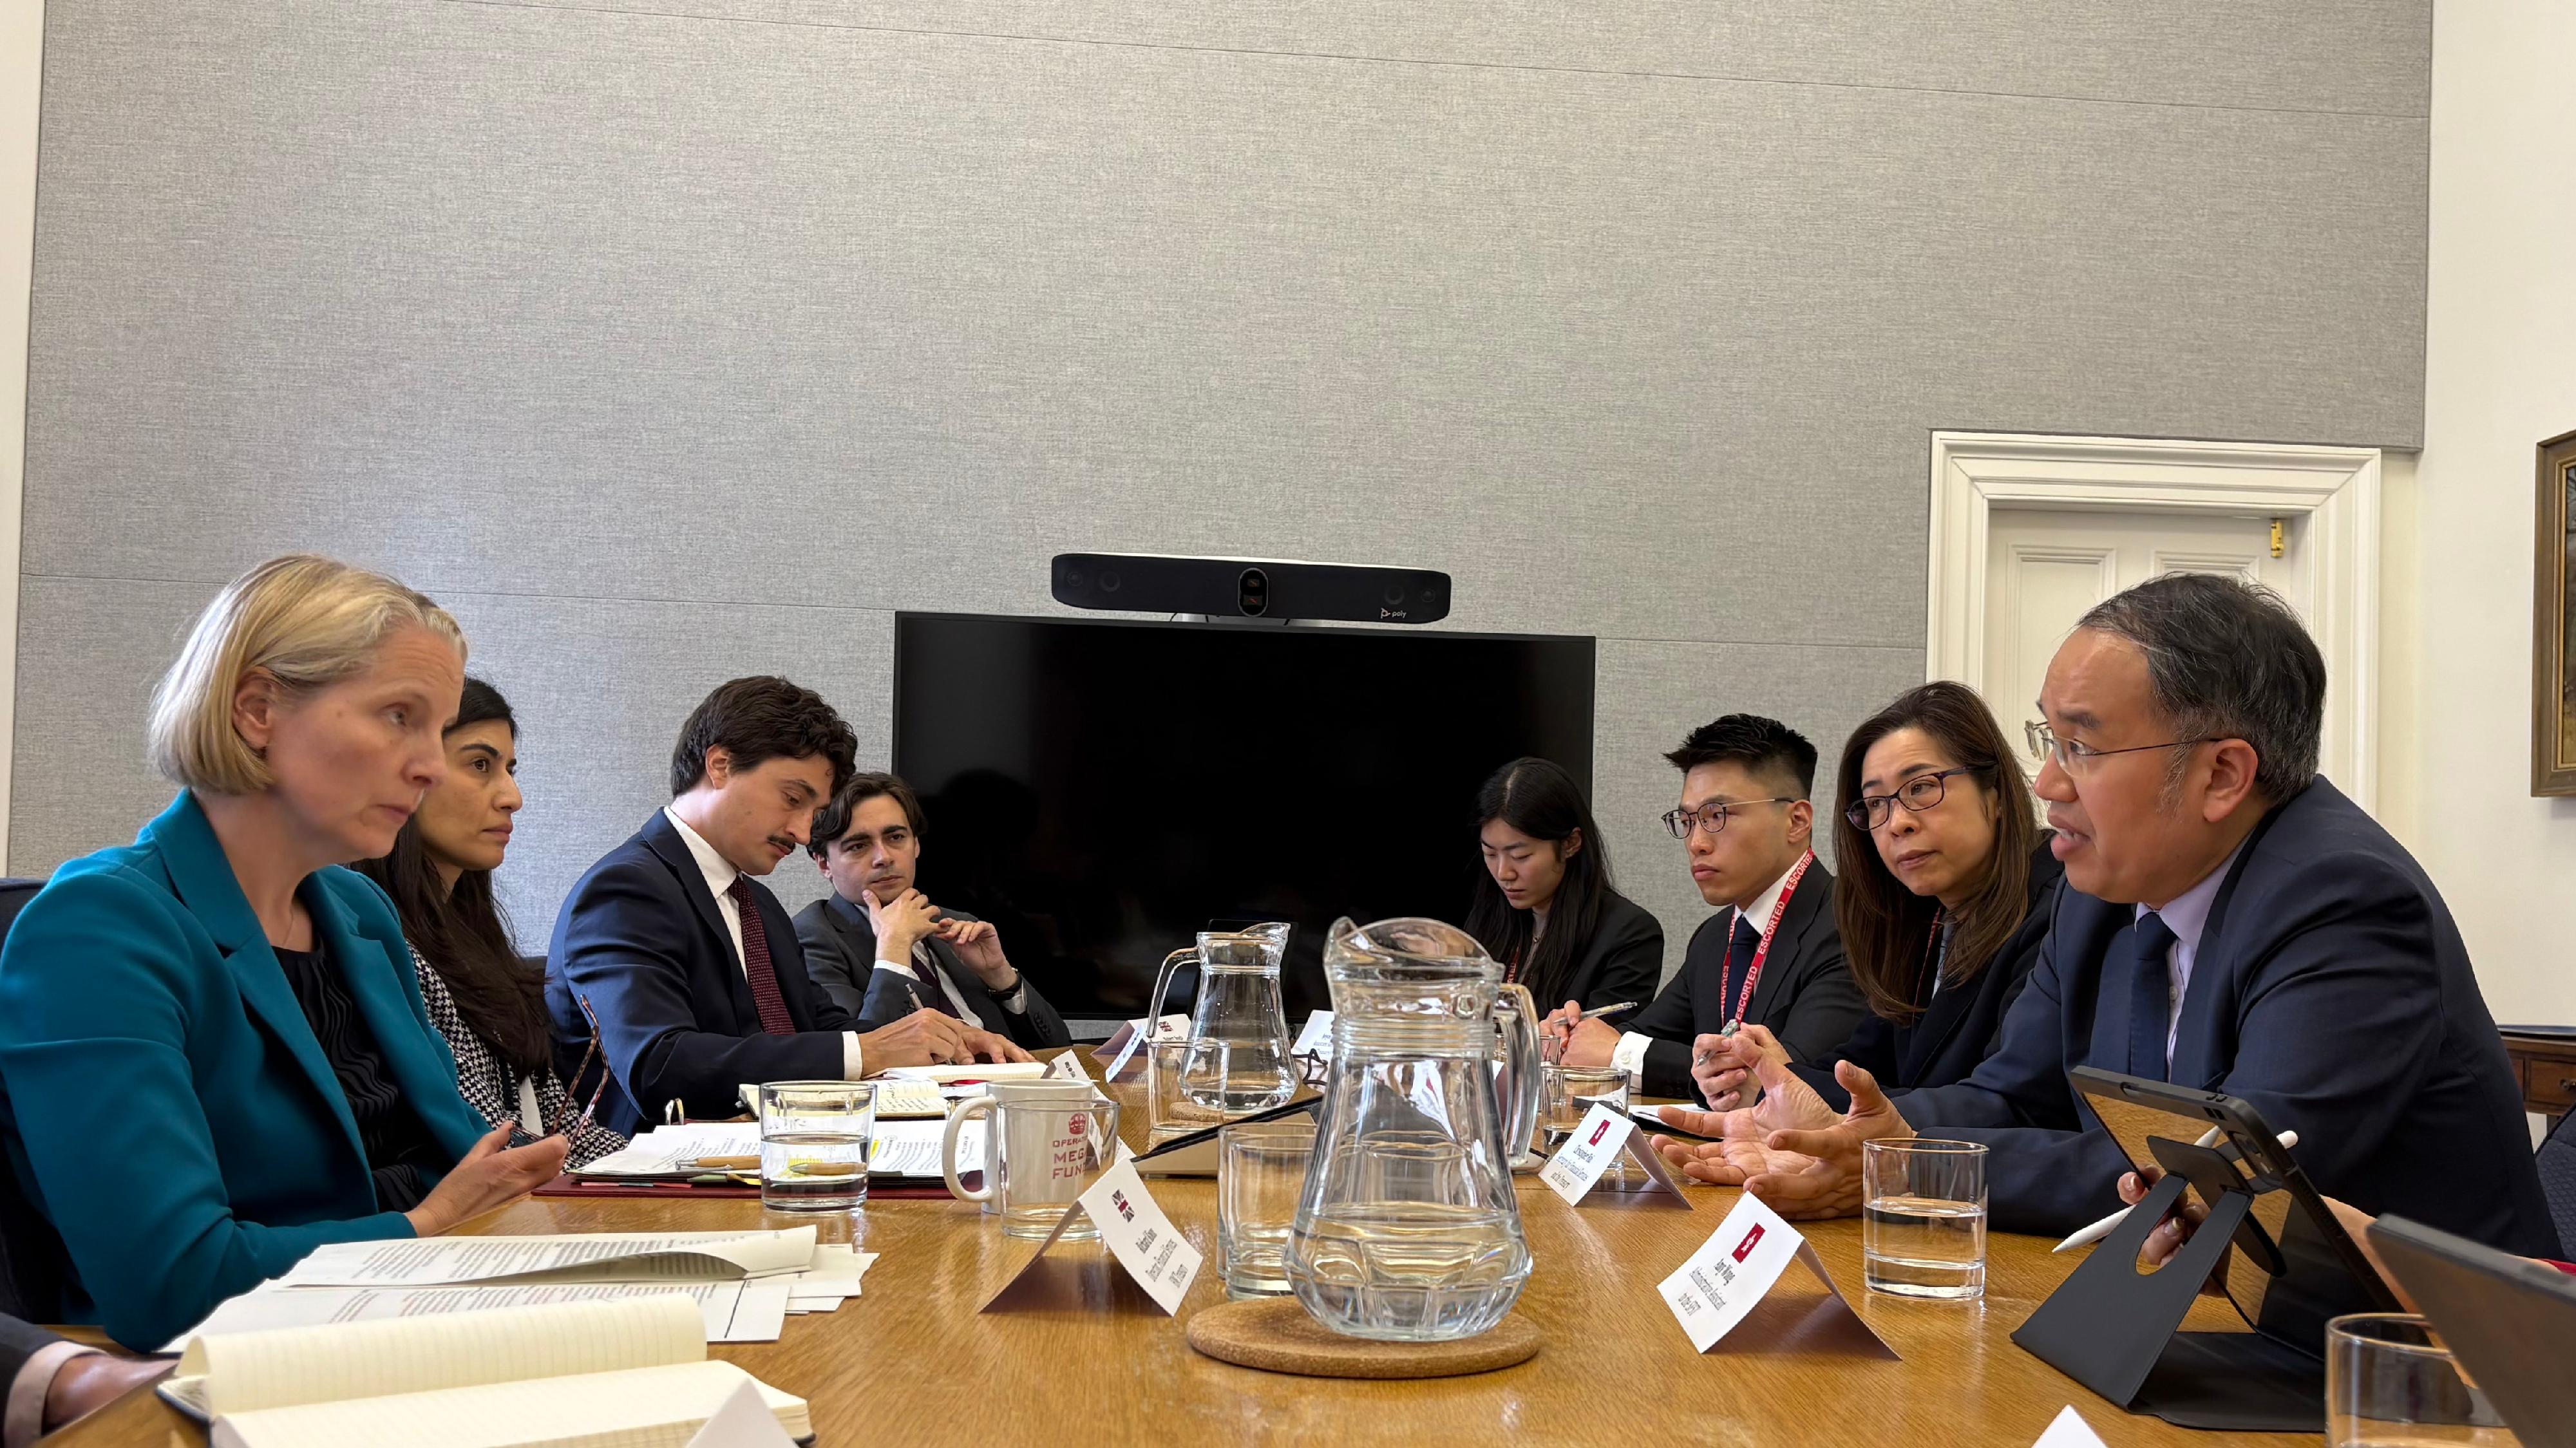
     In the afternoon, Mr Hui met with the Economic Secretary to the Treasury of the UK, Ms Emma Reynolds, and other financial officials to reinforce the financial partnership between the two leading international financial centres. At the meeting, he gave them an update on the latest situation of capital markets in Hong Kong.
      
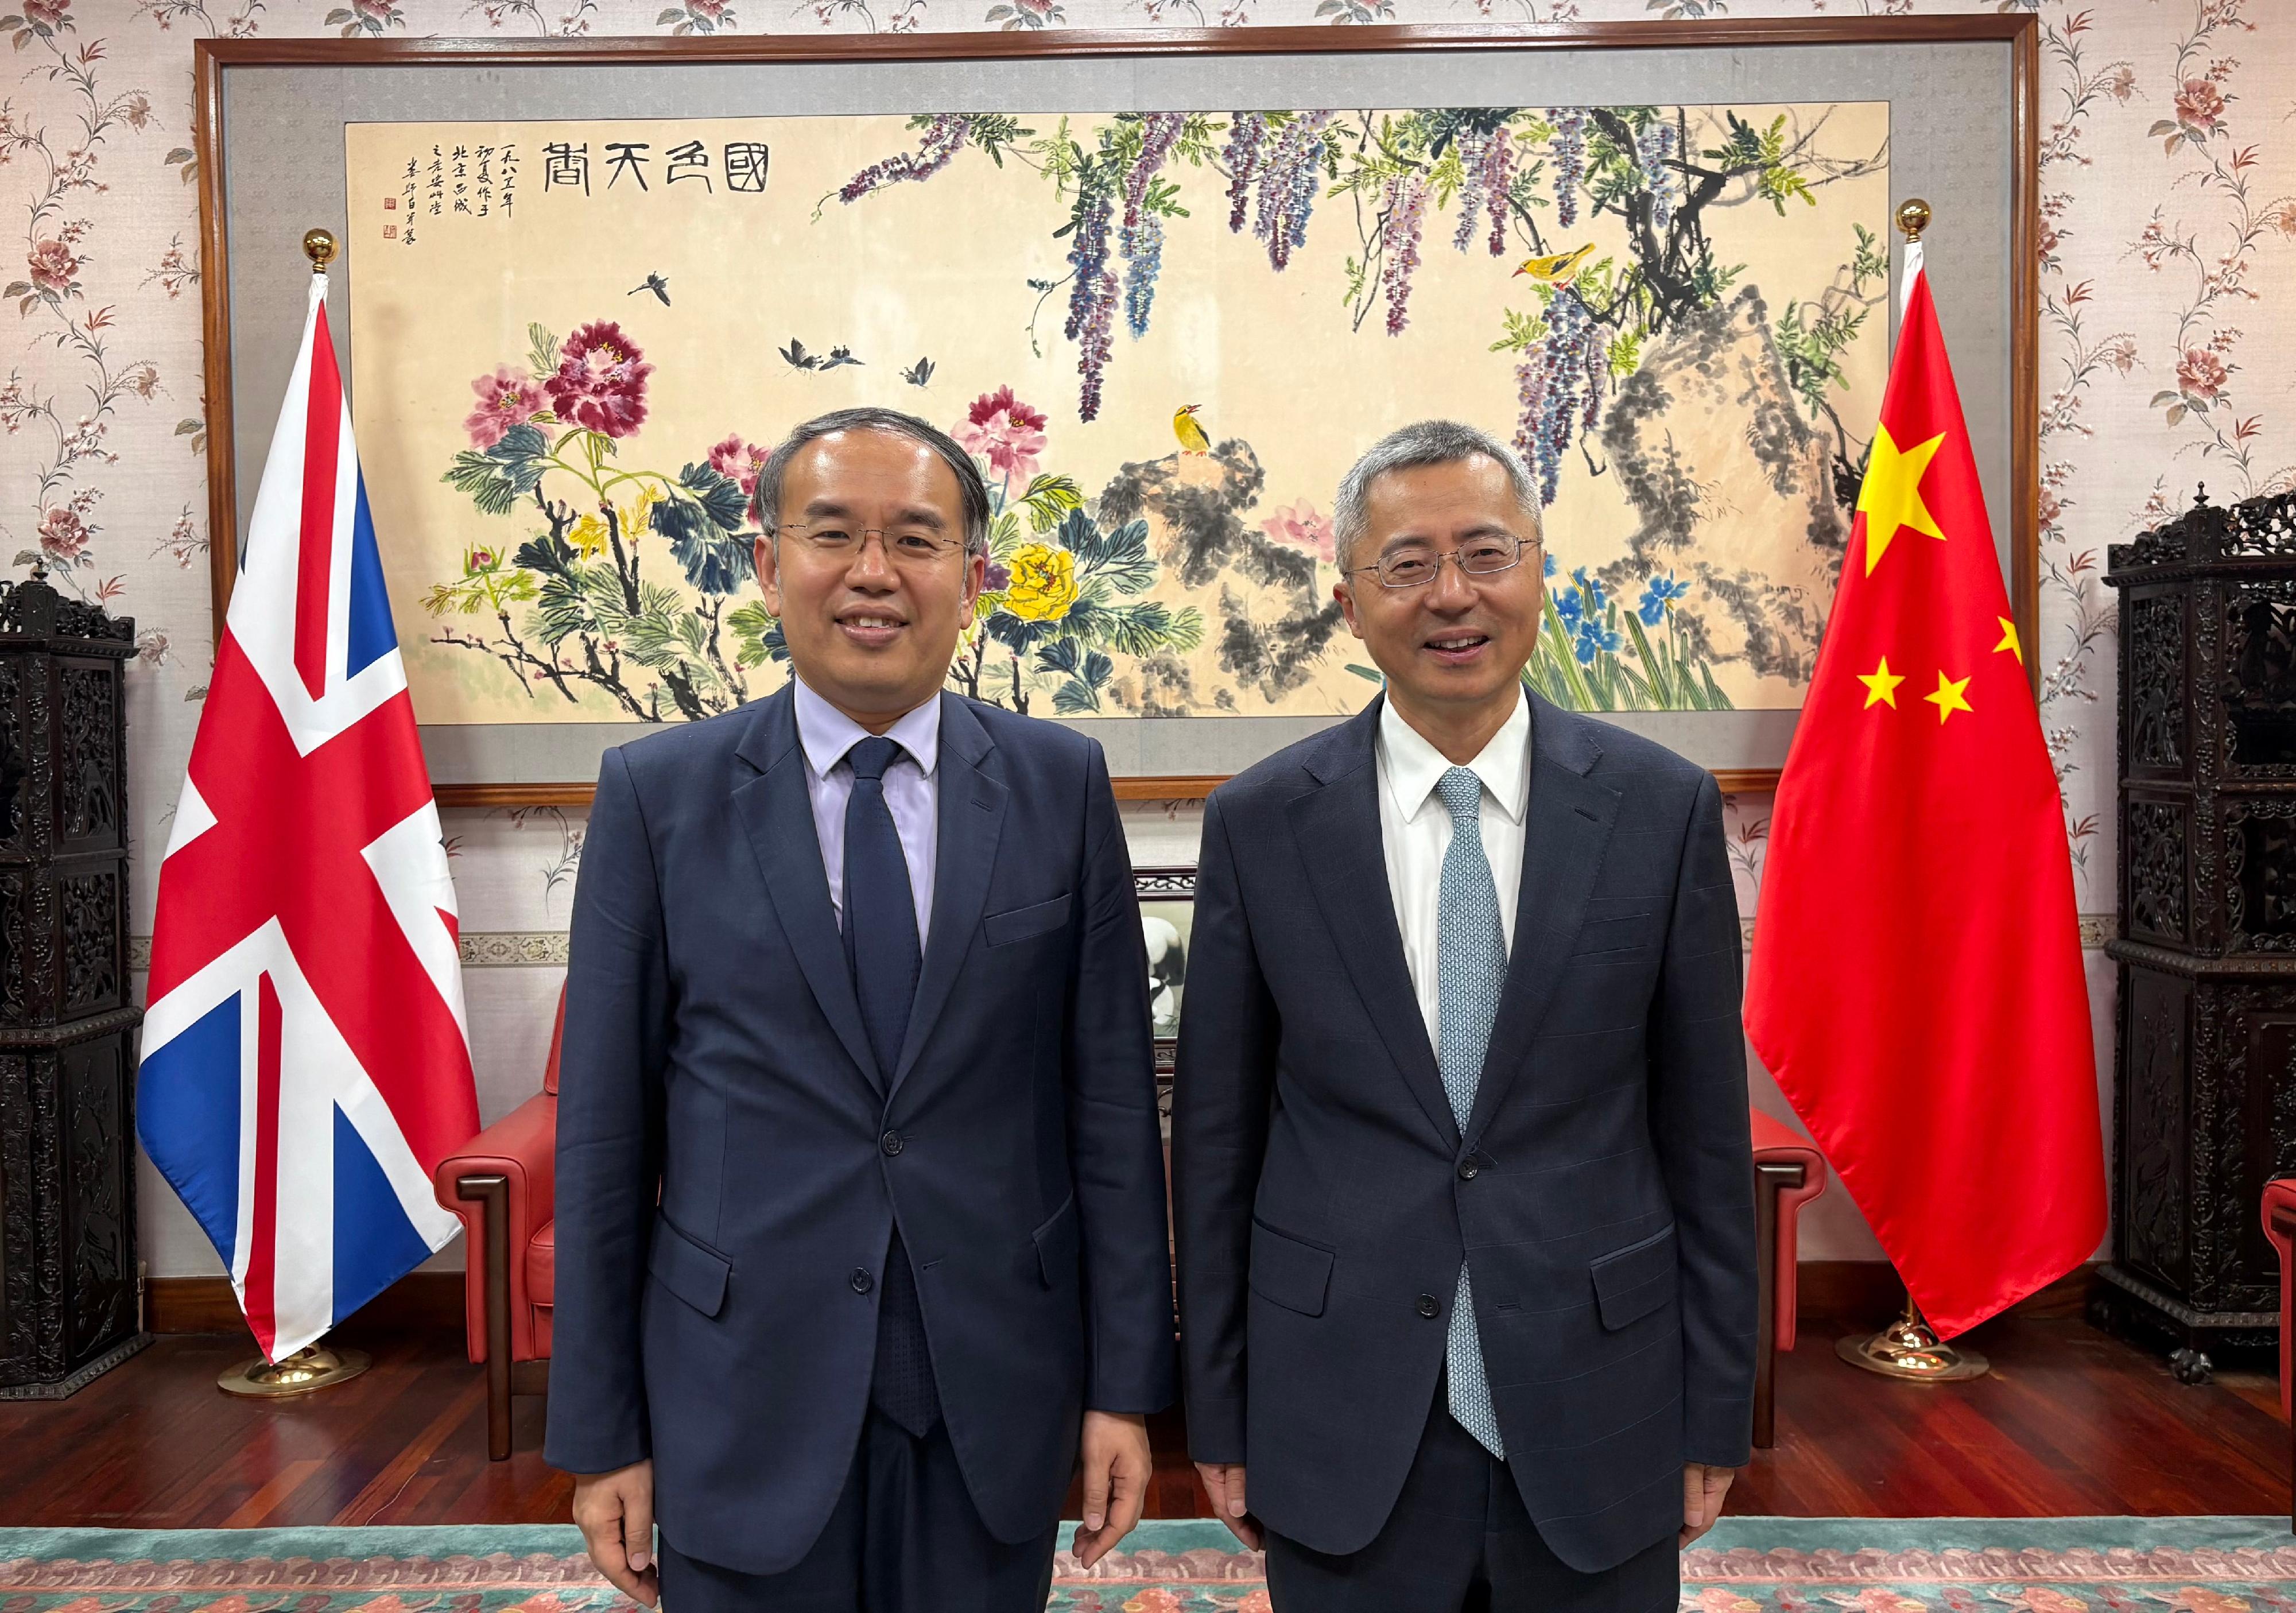
     Mr Hui also paid a courtesy call on Minister of the Chinese Embassy in the United Kingdom Mr Wang Qi.
      
     After concluding the UK leg, Mr Hui proceeded to Oslo, Norway, on June 11 (London time) to continue his visit.

Photo  Photo  Photo  Photo  Photo  Photo  Photo  Photo  Photo  Photo  Photo  Photo  Photo  
read more

LCQ22: Chronic Disease Co-Care Pilot Scheme

     Following is a question by the Hon Stanley Ng and a written reply by the Secretary for Health, Professor Lo Chung-mau, in the Legislative Council today (June 11):

Question:

     The Chronic Disease Co-Care Pilot Scheme (CDCC Pilot Scheme) was launched in November 2023, under which eligible persons are subsidised by the Government to undergo screening in the private healthcare sector and, upon diagnosis of prediabetes, diabetes mellitus (DM) or hypertension (HT), will be taken care of by their family doctors with long-term management. In this connection, will the Government inform this Council:

(1) given that both the General Outpatient Clinic Public-Private Partnership Programme and CDCC Pilot Scheme target chronic diseases and adopt a public-private partnership model, of the following information on each programme/scheme in the past two years: (i) the number of persons covered by the services, the number of participants, the participation rate and the service attendance; (ii) the number of participating private doctors and their participation rate; (iii) the amount of subsidies received by private doctors/clinics; and (iv) the proportion of the amount of subsidies to the costs of standard treatment;

(2) of the following information on private general practitioners and specialists currently participating in CDCC Pilot Scheme: (i) the number and percentage of participants; (ii) the number of services provided; and (iii) the highest, lowest and median amounts of co-payment fees charged for treatment;

(3) whether the Government has set targets for the number of private doctors participating in CDCC Pilot Scheme and their participation rate;

(4) as there are views pointing out that the Government’s recommended co-payment fee of only $150 per consultation for doctors to charge participants under CDCC Pilot Scheme does not take into full account of the professional service costs of specialists, leading to accusations of “overcharging” when specialists charge a co-payment fee more than this amount, whether the Government, in determining the co-payment level, has assessed the differences in service costs between specialists and general practitioners; if not, of the reasons for that; if so, the differences and whether it will consider explaining to members of the public the cost differences between specialists and general practitioners, so as to prevent them from simplifying the fee issue as doctors making profits and bringing pressure from public opinions to bear on doctors;

(5) as some members of the public have relayed that after undergoing tests under CDCC Pilot Scheme, such as thyroid function tests (i.e. thyroid stimulating hormone and free thyroxine), they were found to have diseases other than DM and HT, but the scheme does not subsidise treatment for such diseases, whether the Government will consider expanding the scope of subsidised treatment under CDCC Pilot Scheme or limiting subsidies to only those tests which are directly related to DM and HT, so as to prevent the emergence of unmet medical needs; and

(6) given that an incentive mechanism has been set up under CDCC Pilot Scheme whereby, starting from the second programme year, participants who achieve health incentive targets will enjoy a reduction of co-payment fee with a maximum amount of $150 for their first subsidised consultation in the following programme year, of the number of participants who achieved health incentive targets in the most recent programme year and their percentage in the total number of scheme participants; whether the Government has assessed the effectiveness of implementing the incentive mechanism?

Reply:

President,

     In consultation with the Primary Healthcare Commission and the Hospital Authority (HA), the replies to the respective parts of the question raised by the Hon Stanley Ng are as follows:

(1), (2) and (3)

General Outpatient Clinic Public-Private Partnership Programme (GOPC PPP)

     The HA has implemented the GOPC PPP by phases since mid-2014 to subsidise clinically stable patients with hypertension (HT) and/or diabetes mellitus (DM) (with or without hyperlipidaemia) to choose to receive follow-up consultations at General Out-patient Clinics (GOPCs), or to receive primary healthcare services from private services providers in the community, with a view to relieving the service pressure off of the public GOPCs. Patients fulfilling specified clinical criteria and programme requirements and have been attending the HA’s GOPCs for at least 12 months will be invited to join voluntarily. The table below lists the number of Participating Service Providers (PSPs) and participating patients in the GOPC PPP in the past two years:
 

GOPC PPP 2023-24 2024-25 2025-26
(as at end-May 2025)
Number of PSPs 656 622 623
Number of patients 54 716 51 228 50 945

     Patients participating in the GOPC PPP are currently required to pay the HA’s GOPC fee for each consultation (i.e. $50). Each participating patient will receive up to 10 subsidised consultations per year, including treatments for both chronic and episodic illnesses. Upon private doctor’s referral, they can also receive X-ray examinations provided by the HA, or specified laboratory tests and electrocardiography at the HA’s designated private laboratories. When the HA’s new fees (including the GOPC and Family Medicine Specialist Clinic (FMSC) services, will be unify under the name of Family Medicine Outpatient (FMOP) Services, at $150 per consultation and $5 per drug item per four-week period) come into effect on January 1, 2026, the new fees will also be applicable to GOPC PPP patients. The table below lists the consultation subsidy and quarterly drug subsidy received by each patient participating in the GOPC PPP in the past two years:
 
  2023-24 2024-25 Present
Consultation subsidy
(Per subsidised consultation)
$262 $266 $266
Drug subsidy
(Per quarter)
$123 $125 $125

Chronic Disease Co-Care Pilot Scheme (CDCC Pilot Scheme)

     The Government launched the CDCC Pilot Scheme in November 2023, providing subsidised DM and HT screening services in the private healthcare sector to Hong Kong residents aged 45 or above with no known medical history of DM or HT, so as to achieve the chronic disease management objectives of “early prevention, early identification and early treatment”.  

     The CDCC Pilot Scheme has been well received since its launch. As at May 31, 2025, around 131 200 individuals in total have enrolled in the Scheme, and it is expected that the target of having 200 000 participants during the three-year pilot period can be achieved earlier than expected. More than 74 900 participants (i.e. about 60 per cent) have completed the screenings (Note 1), and around 31 100 of those who had completed screenings (i.e. about 40 per cent) have been diagnosed with prediabetes (Note 2), DM, HT or hyperlipidaemia. The latter patients can proceed to the treatment phase and will be subsidised by the Government to continue their treatment with self-selected Family Doctors (FDs), and subject to their health conditions, be offered prescribed medication and follow-up care at nurse clinics and allied health services.

     At the same time, the Government is expanding the CDCC Pilot Scheme in phases to designated GOPCs to provide the underprivileged group (recipients of the Comprehensive Social Security Assistance Scheme, recipients of the Old Age Living Allowance aged 75 or above, or persons holding a valid medical fee waiver certificate) with preventive screening and care services for chronic diseases under the Scheme, with full or partial waiver of fees according to their eligibility. The first phase of the service was launched in seven GOPCs in March 2025 (see Annex), with plans to extend the services to have GOPCs in all 18 districts to provide relevant services by the end of this year. As at May 30, 2025, there were more than 1 000 attendances at the relevant GOPCs for screening and care services for the “three highs” (i.e. high blood pressure, high blood sugar and high cholesterol).

     As at May 29, 2025, over 640 FDs (including specialists) in the private sector have participated in the CDCC Pilot Scheme, covering 859 service points. The table below lists the amount of subsidy and the participants’ co-payment fee that an FD can receive per patient during the screening and treatment phases of the CDCC Pilot Scheme:


Consultation Subsidy Participant
Co-payment Fee
Drug Subsidy (Note 3)
Screening phase $196
(One-off subsidy)
As determined by FD
 $120 or less
(One-off)
Not applicable
Treatment phase $166
(Per subsidised consultation)
As determined by FD
Government recommendation: $150
(Per subsidised consultation)
$105
(Per quarter)
Note 3: Drugs prescribed must be chronic disease drugs included in the CDCC Pilot Scheme Drug List.

     The range of co-payment fee in the treatment phase set by FDs is set out in the table below:
 
Co-payment level (Note 4) Number of FDs Percentage (Note 5)
$0 – $50 79 (Note 6) 12.3%
$51 – $150 377 (Note 7) 58.7%
$151 – $250 103 16.0%
$251 – $350 66 10.3%
$351 – $450 8 1.2%
$451 – $550 4 0.6%
$551 – $999 5 (Note 8) 0.8%
Note 4: The Government recommended consultation co-payment fee in the treatment phase is $150 per consultation.
Note 5: Percentages may not add up to 100 per cent due to rounding.
Note 6: Three FDs set co-payment fee at $0.
Note 7: 370 FDs set co-payment fee at $150.
Note 8: The highest co-payment fee is $800.

     The Government will strengthen the dual-track, complementary and collaborative model of public and private primary healthcare by providing chronic disease screening and management through private sector FDs and the district health network to the public on a co-payment basis. At the same time, the Government will reposition the HA’s GOPCs to provide comprehensive primary healthcare services specifically for the underprivileged group. To underscore the direction of primary healthcare development, the HA will unify its GOPC and FMSC services under the new name of FMOP Services within this year. The Government will also adopt a primary healthcare service model to gradually integrate suitable patients under the GOPC PPP into the CDCC Pilot Scheme for continued care.

(4) The Government considered a wide range of factors when determining the subsidy amount for the CDCC Pilot Scheme, including market prices, affordability of the public, service demand and options, as well as the attractiveness of the Scheme. 

     The core service of the CDCC Pilot Scheme is chronic disease management, and the content of the service should not vary depending on whether the FD has specialist qualifications or not. Under the existing system, participating FDs may set their own co-payment fee based on the content of their services. The Government completed the preliminary review of the CDCC Pilot Scheme in March 2024 and has introduced a number of improvement measures based on the results of the review, including allowing participating FDs (regardless of specialists or general practitioners) to set a co-payment fee of $120 or less in the screening phase, and to determine the consultation co-payment fee during the treatment phase on their own. The relevant fees can be adjusted once annually according to the established mechanism. The Government will reconsider the subsidy arrangement if there is a difference in the designated services provided by specialists and general practitioners under the CDCC Pilot Scheme in future.

     The Government has uploaded a list of all participating FDs, along with their basic information (including practice locations and participation in other Government-subsidised primary healthcare programmes (such as the Elderly Health Care Voucher Scheme)) and their designated consultation co-payment fees during the screening phase and treatment phase onto the dedicated website for the CDCC Pilot Scheme, to allow the public to compare clearly and make informed choices. The Government encourages participants to make good use of the information on the dedicated website. Staff at District Health Centres/Expresses can also provide assistance. The Government will continue to monitor the implementation of the Scheme to ensure that the fee mechanism protects the interests of the public while reasonably reflecting the value of medical professional services, and will consider enhancing and refining the relevant mechanism as necessary.

(5) The CDCC Pilot Scheme currently focuses on the screening and management of the “three highs” (i.e. high blood pressure, high blood sugar and high cholesterol). Participants who are found to have “three highs” problems, as well as other health problems (e.g. thyroid dysfunction) or other medical conditions through the tests of the Scheme, can receive treatment for both the target chronic diseases and episodic illnesses concurrently at any of the subsidised consultations during the treatment phase. The CDCC Pilot Scheme has a basic-tier drug list covering the drugs for treating the “three highs” and for episodic illnesses (e.g. antibiotics and drugs for treating associated health problems). Under Government subsidy, participants prescribed with the drugs on the list will not be required to pay for such medication. The Government encourages participants to maintain a long-term relationship with their paired FD, who will follow up with them on their health status, including treatment of diseases other than DM,HT and hyperlipidaemia.

     The Government will regularly review the scope of primary healthcare services and the CDCC Pilot Scheme service scope based on considerations such as scientific evidence and resource utilisation, with a view to promoting multidisciplinary care and providing wider coverage and better continuity of healthcare services for Scheme participants. In the long run, the CDCC Pilot Scheme will gradually expand to cover more target diseases and health conditions. Related support services include a comprehensive network of nursing, allied health, pharmacy, laboratory, pharmaceutical and radiological diagnostics services.

(6) The CDCC Pilot Scheme has built in a doctor-patient partnership incentive mechanism with a view to encouraging FDs and participants to actively engage in the treatment process. All participants who have achieved certain health incentive targets (such as having their health indexes monitored and subsequently uploaded to the eHealth mobile application, attended follow-up consultations regularly, completed health education programmes or undergone laboratory investigations as advised) will enjoy a reduction of co-payment fee with a maximum amount of $150 (Note 9) for their first subsidised consultation in the following participant programme year. FDs who fulfil the pre-requisite requirements (i.e. meeting a pre-defined percentage of patients who achieved targets in regulating their levels of blood sugar and blood pressure) can also receive corresponding incentive payments (Note 10).  

     The assessment of the incentive mechanism will start from the second participant programme year of Scheme participants upon entering the treatment phase. Since the CDCC Pilot Scheme has only been implemented for a year and a half, no Scheme participant has completed the full assessment cycle, hence the number and proportion of participants who have reached the targets are not available at this stage. The Government will analyse the effectiveness of the incentive mechanism after the first batch of participants have completed their second participant programme year.

Note 1: The CDCC Pilot Scheme screened for DM and HT in the initial phase (before March 28, 2025), and was later expanded to include blood lipid screening. Therefore, some of the participants who completed the screening were screened for DM and HT only, while the rest were screened for the “three highs”.

Note 2: Prediabetes with glycated haemoglobin level of 6.0 to 6.4 per cent or fasting plasma glucose level of 6.1 to 6.9 mmol/L.

Note 9: The Government recommended consultation co-payment fee in the treatment phase.

Note 10: The calculation of incentive payment is 15 per cent of the total amount derived from the number of actual attendance of the subsidised consultations by the patients who have achieved their targets, the Government consultation subsidy and the recommended co-payment fee. read more

LCQ4: Quarantine arrangements for imported cats and dogs

     Following is a question by Professor the Hon Priscilla Leung and a reply by the Secretary for Environment and Ecology, Mr Tse Chin-wan, in the Legislative Council today (June 11):
 
Question:

     The Agriculture, Fisheries and Conservation Department has updated the quarantine arrangements for cats and dogs this month. Cats and dogs imported from the Mainland that meet the relevant quarantine requirements (including obtaining satisfactory results from testing conducted by recognised laboratories on the Mainland and having an animal health certificate issued by Mainland official veterinarians) will have their quarantine period significantly reduced from the current 120 days to 30 days upon arrival in Hong Kong. In this connection, will the Government inform this Council:

(1) given that imported cats and dogs are currently required to be quarantined at designated quarantine facilities, whether the authorities will consider introducing a flexible mode of quarantine, e.g. home quarantine for the entire period, or a mixed mode involving “quarantine at a facility for the first 15 days and home quarantine for the remaining 15 days”, with a view to relieving the financial burden on animal owners and enhancing the efficiency on the use of facilities;

(2) as there are views that the numbers of imported cats and dogs may increase significantly after the quarantine period is reduced, whether the Government has assessed if the numbers of quarantine facilities in Hong Kong and recognised laboratories on the Mainland are sufficient to cope with the demand, and how the authorities will ensure the quality of the relevant testing; and

(3) as there are views pointing out that there is a significant price difference between pet cats and dogs on the Mainland and in Hong Kong, and that updating the quarantine arrangements may increase the numbers of pet-keeping households in Hong Kong in the long run, whether the Government has assessed if there are sufficient veterinary equipment, clinics and hospitals in Hong Kong?
 
Reply:

President,
 
     Rabies is a contagious disease that causes fatality to mammals (including humans) and no specific treatment is available at present. To prevent the introduction of animal diseases such as rabies into Hong Kong, the Agriculture, Fisheries and Conservation Department (AFCD) regulates the import of live animals through a permit system, and controls the import of cats and dogs under the Public Health (Animals and Birds) Regulations (Cap. 139A) and the Rabies Regulation (Cap. 421A) to protect public and animal health. Under effective control measures, Hong Kong has long been widely recognised as a rabies-free place by other places. Animals of Hong Kong generally face less stringent quarantine requirements when entering other places. 
 
     On the quarantine arrangements of imported cats and dogs, the AFCD classifies places into different groups according to different risk of rabies, with reference to information about the surveillance of animal diseases from the World Organisation for Animal Health. Group I and Group II places are respectively rabies-free places and places where rabies cases are few and under effective control. Since these places are considered of lower risk of rabies, the imported cats and dogs are exempted from quarantine upon fulfilling specified requirements. Places that do not meet the requirements of Group I or Group II, or where their situations cannot be determined, will be included in Group III. Cats and dogs imported from these places are required to undergo a quarantine of not less than 120 days before December 2024.
 
     Since December 2024, the AFCD has divided Group III into Group A and B according to the results of risk assessment. Quarantine period for cats and dogs of Group IIIA is significantly shortened from 120 days to 30 days upon their arrival in Hong Kong, provided that they meet the relevant quarantine requirements including that the animals must be vaccinated against rabies, conducted a valid rabies neutralising antibody titre test, had an animal health certificate issued or endorsed by a government veterinary officer of the place of export. The Macao Special Administrative Region, Lithuania and the Mainland have been included in Group IIIA successively. As regards Group IIIB places, since the risk of rabies is higher or uncertain, and the incubation period of rabies can be up to several months, the quarantine period for cats and dogs imported from those places is maintained at not less than 120 days.
 
     The reply to the question from Professor the Hon Priscilla Leung is as follows:
 
(1) As mentioned just now, as long as cats and dogs imported from the newly added Group IIIA places (including the Mainland) meet the relevant quarantine requirements and hold an animal health certificate issued by an official veterinarian from the Mainland, the quarantine period upon arrival in Hong Kong will be significantly reduced from 120 days to 30 days. Because of this change, the cost of quarantine facilities that the owners of these cats and dogs have to pay has been greatly reduced to one-quarter of the previous cost, at the same time, the turnover rate of quarantine facilities will increase to four times than that of the past. The waiting time for quarantine facilities will be reduced correspondingly, and the usage effectiveness will be increased significantly.
 
     As regards the quarantine arrangements, the current international practice is to isolate cats and dogs in officially supervised quarantine facilities to ensure that the animals will not have direct or indirect contact with other animals during the quarantine period, so as to avoid the transmission of animal disease into the community. As the mortality rate of rabies is close to 100 per cent, and animals have the opportunity to come into contact with other people or animals when they are quarantined in private premises, this will bring to them higher risk. Hence from a risk management perspective, home quarantine arrangement is not appropriate. The Department will continue to make reference to the latest animal disease situation announced by the World Organisation for Animal Health, and timely optimise the quarantine requirements for imported cats and dogs, taking into account factors such as international practices, operational experience and risk assessment.
 
(2) To facilitate animal owners to bring their pet cats and dogs to Hong Kong, the Government has not only optimised the quarantine requirements for cats and dogs, but also increased the number of quarantine facilities. The new quarantine facilities at the Kowloon Animal Management Centre under the AFCD have been put into service in May this year. The quarantine facilities provided for cats and dogs have increased from 21 and 20 to 34 and 30 respectively. Further, taking into account that the shortened quarantine period has increased the turnover speed to four times than that of the past, the handling capacity of the AFCD’s quarantine facilities could be increased by as much as six to seven times than that of the past. In addition, the AFCD encourages private animal welfare organisations to provide quarantine facilities for cats and dogs, and is reviewing the application of the Hong Kong Society for the Prevention of Cruelty to Animals (SPCA). It is expected that the quarantine facility will be put into service in the middle of this year. The Department will also provide information and assistance to other private animal welfare organisations interested in operating quarantine facilities for cats and dogs. On the basis of the above improvement measures, it is expected that the quarantine facilities will be able to meet the demand.
 
     As regards the number and testing quality of recognised Mainland laboratories, after discussions with the Mainland authorities and taking into account the regional distribution and level of recognition of the laboratories in the Mainland, the AFCD has recognised four Mainland laboratories in Beijing, Shanghai, Guangzhou and Changchun for conducting rabies antibody titre tests for cats and dogs. All four laboratories are recognised by the Mainland authorities and the European Union, hence the quality of testing is assured. The AFCD will closely monitor the situation and will discuss with the Mainland authorities to adjust the list of approved laboratories when necessary.
 
(3) The Veterinary Surgeons Board of Hong Kong (VSB) is a statutory body established under the Veterinary Surgeons Registration Ordinance (Cap. 529), and is responsible for the regulation, registration and disciplinary control of veterinary surgeons, to ensure a high standard of veterinary services in Hong Kong. The VSB learns about the overall veterinary services through data gathered in the regulation of the veterinary profession.
 
     The number of registered veterinary surgeons (RVS) has been consistently on the rise since 2015, from 823 in 2015 to 1 364 in April this year, representing an increase of 65 per cent. Moreover, RVS comprises many specialties, such as small animal internal medicine and surgery, dermatology, cardiology, neurology and veterinary pathology. Apart from private veterinary clinics, the City University of Hong Kong and some animal welfare organisations, such as the SPCA, also provide veterinary services, therefore animal owners should be able to find appropriate veterinary services for their pets.
 
     Thank you, President. read more

LCQ19: Immigration Arrangements for Non-local Graduates

     Following is a question by Dr the Hon Dennis Lam and a written reply by the Secretary for Education, Dr Choi Yuk-lin, in the Legislative Council today (June 11):
      
Question:

     At present, the Immigration Arrangements for Non-local Graduates (IANG) adopt a “2+3+3” year mode of stay. It is learnt that earlier this year, some of those who were admitted to Hong Kong for employment through IANG (e.g. those whose employment contracts were about to expire) were unable to obtain three-year visa renewals smoothly when extending their stay. In this connection, will the Government inform this Council:

(1) of the respective numbers of first applications for IANG and applications for extension of stay under IANG received, approved and rejected by the Immigration Department (ImmD), as well as the number of persons who were admitted to Hong Kong as dependants under IANG in the past three years;

(2) of the following information on the full-time employment of the persons who have been granted IANG visas and their dependants mentioned in (1): (i) the major industries and job types in which they are engaged, and (ii) the highest, lowest and median amounts of monthly salaries;

(3) whether it has assessed the long-term effectiveness of IANG in attracting and retaining talent; if it has assessed, of the details; if not, the reasons for that;

(4) whether ImmD has made any adjustment to the vetting and approval of applications for extension of stay by IANG visa holders at present; if so, of the details; if not, why some IANG visa holders have relayed that their applications for extension of stay have only been granted for a few months; and

(5) whether it has considered providing transitional support (e.g. arranging short-term accommodation and setting up a dedicated recruitment website, etc) for persons who have just been granted IANG visas in the future, so as to assist them in adapting the live in Hong Kong; if so, of the details; if not, the reasons for that?

Reply:

President,

     Applicants who are/were non-local students and have obtained an undergraduate or higher qualification in a full-time and locally-accredited programme in Hong Kong may apply to stay/return and work in Hong Kong under the Immigration Arrangements for Non-local Graduates (IANG). The Government has extended the IANG on a pilot basis to cover graduates with a bachelor’s degree or higher qualification from Hong Kong universities’ campuses in Mainland cities of the Guangdong-Hong Kong-Macao Greater Bay Area (GBA).

     After consultation with the Immigration Department and the Labour and Welfare Bureau, our consolidated replies to Dr the Hon Dennis Lam’s questions are as follows: 

(1) The numbers of applications received, approved and refused under the IANG in the past three years are tabulated below:  
 

Type of Applications 2022 2023 2024
New applications Number of applications received 10 936 27 295 26 973
Number of applications approved 10 391 26 089 25 475
Number of applications refused 21 16 24
Extension of stay applications Number of applications received 11 032 11 637 6 985
Number of applications approved 10 619 11 189 6 592
Number of applications refused 6 20 53
Dependant application Number of applications approved 1 851 4 702 6 600

Note: Applications approved/refused in a year may not all be received in the same year.

(2) At present, over 90 per cent of those coming to or staying in Hong Kong under the IANG are fresh graduates. They are not required to have secured offers of employment in Hong Kong upon application. However, when applying for an extension of stay, they are required to have taken up employment in Hong Kong that are at the levels commonly taken up by degree holders and the remuneration packages are on par with the market level. For those who have established or joined in business in Hong Kong, they are required to produce proof of their business upon application for an extension of stay.

     The breakdown of the numbers of approved applications for an extension of stay under the IANG by industry/sector is tabulated below:
 
Industry/sector 2022 2023 2024
Financial services 4 298 4 338 2 834
Academic research and education 1 407 1 873 863
Commerce and trade 1 611 1 312 818
Information technology 495 477 241
Telecommunications 209 351 194
Engineering and construction 211 264 173
Legal services 164 196 111
Medical and healthcare services 124 136 104
Architecture/Surveying 97 112 60
Manufacturing industries 29 70 52
Tourism 25 47 39
Catering services 34 41 24
Arts/Culture 46 49 20
Recreation and sports 26 21 14
Traditional Chinese medicine 8 16 10
Biotechnology 32 40 8
Others 1 803 1 846 1 027
Total 10 619 11 189 6 592

     The Immigration Department does not maintain other breakdowns of statistics mentioned in the question. 
     
(3) Since its launch in 2008, the IANG has received positive response and helped Hong Kong attract and retain talent as well as expanding the talent pool. As at the end of April 2025, a total of 177 567 applications have been received. Among them, 172 043 applications have been approved, with over 90 per cent being recent non-local graduates and 2 825 applications coming from the graduates of the GBA campuses of Hong Kong universities. The statistics on entrants admitted to Hong Kong under the IANG who eventually acquired the right of abode in the past five years are tabulated as follows: 
 
Admission policy/scheme 2020 2021 2022 2023 2024
IANG 3 117 3 449 3 495 4 441 4 128

Note: The figures are based on the applicants’ status in Hong Kong at the time of application for the right of abode.

     With the development of the GBA, it has become a trend for Hong Kong universities to set up campuses in Mainland cities of the GBA through joint ventures, and their graduates will become an important source of talent in the GBA. Starting from the end of 2022, the Government has extended the IANG on a pilot basis to cover graduates with a bachelor’s degree or higher qualification from Hong Kong universities’ campuses in Mainland cities of the GBA, so as to attract outstanding talent from these institutions to come to Hong Kong for employment and further boost Hong Kong’s human resources and competitiveness. The Chief Executive announced in his Policy Address 2024 to extend the pilot arrangement for two years. This measure not only fosters the exchange of talents in the GBA, but also meets the needs of economic development in the GBA. We will continue to monitor the implementation of the IANG, particularly the response to the inclusion of graduates of Hong Kong universities’ GBA campuses under the IANG, and review its effectiveness in due course.

(4) Upon applying for an extension of stay by persons admitted under the IANG, non-local graduates/GBA campus graduates are required to have taken up employment in Hong Kong which is at a level commonly taken up by degree holders and the remuneration package is at the market level. For those who have established or joined in a business in Hong Kong, they are required to produce proof of their business. When assessing an application for an extension of stay, various factors related to the applicant’s employment or business conditions will be considered, including but not limited to the remuneration package or the operation and development of the business, the economic benefits brought by the employment or business, and the duration of stay in Hong Kong, etc. Successful applicants will normally be granted an extension of stay on time limitation only without other conditions of stay for not more than three years, or until the expiry of their employment contract in Hong Kong, whichever is the shorter. For those who have established or joined in a business in Hong Kong, the length of their extension of stay to be granted will be determined based on the comprehensive consideration of the operating conditions of the relevant business.

(5) Since its establishment on October 30, 2023, the Hong Kong Talent Engage (HKTE) has been providing comprehensive one-stop support to talents coming to or staying in Hong Kong under various talent admission schemes (including the IANG) through both online and offline means. Apart from providing comprehensive information on living and working in Hong Kong as well as handling enquiries from outside talent through its online platform (www.hkengage.gov.hk), the HKTE organises with working partners a variety of online and offline activities such as job fairs, themed seminars, workshops (including Cantonese learning classes) and social integration activities (including the Talent+ Volunteer Programme) to share information on entrepreneurship, employment as well as other living tips and to facilitate the incoming talent to settle in Hong Kong and integrate into the city as soon as possible. The online platform features about 5 000 real-time quality job opportunities daily for which talent can apply directly through the platform. Moreover, the online platform is connected to about 90 designated working partners of the HKTE to provide recommendations and services in areas such as job seeking, accommodation, education, integrated settlement, banking and insurance, business and corporate as well as networking and community, etc through online matching tools. read more